For the past several years, much of the conversation around artificial intelligence in wealth management has focused on efficiency.
Can AI summarize a meeting? Draft an email? Search a knowledge base? Prepare for a client review faster?
Those applications matter. But they may also be obscuring the much larger shift taking place.
In its 2026 Global Wealth Report, Boston Consulting Group (BCG) argues that AI is becoming a structural force in wealth management, not simply an incremental productivity tool. AI is already being applied to financial planning, portfolio management, compliance documentation and increasingly complex workflows.
That distinction matters. The first chapter of AI was about helping advisors complete individual tasks faster. The next chapter is about changing how much advice one advisor can deliver.
And if that happens at scale, the economics of wealth management begin to change with it.
- The scarce resource in wealth management is advisor capacity
- Imagine giving every advisor another day in the week
- AI can move the advisor up the value chain
- Planning is where the economics become especially interesting
- But AI alone is not enough
- The real divide will be between AI-enabled and AI-first firms
- The ceiling on advice is moving
The scarce resource in wealth management is advisor capacity
Advice has traditionally been difficult to scale.
Every additional client creates additional work. More meetings. More preparation. More documentation. More analysis. More servicing. More follow-up.
Technology has improved many of these processes over the years, but the basic equation has remained largely intact: serving more clients generally requires more people.
AI is changing that equation.
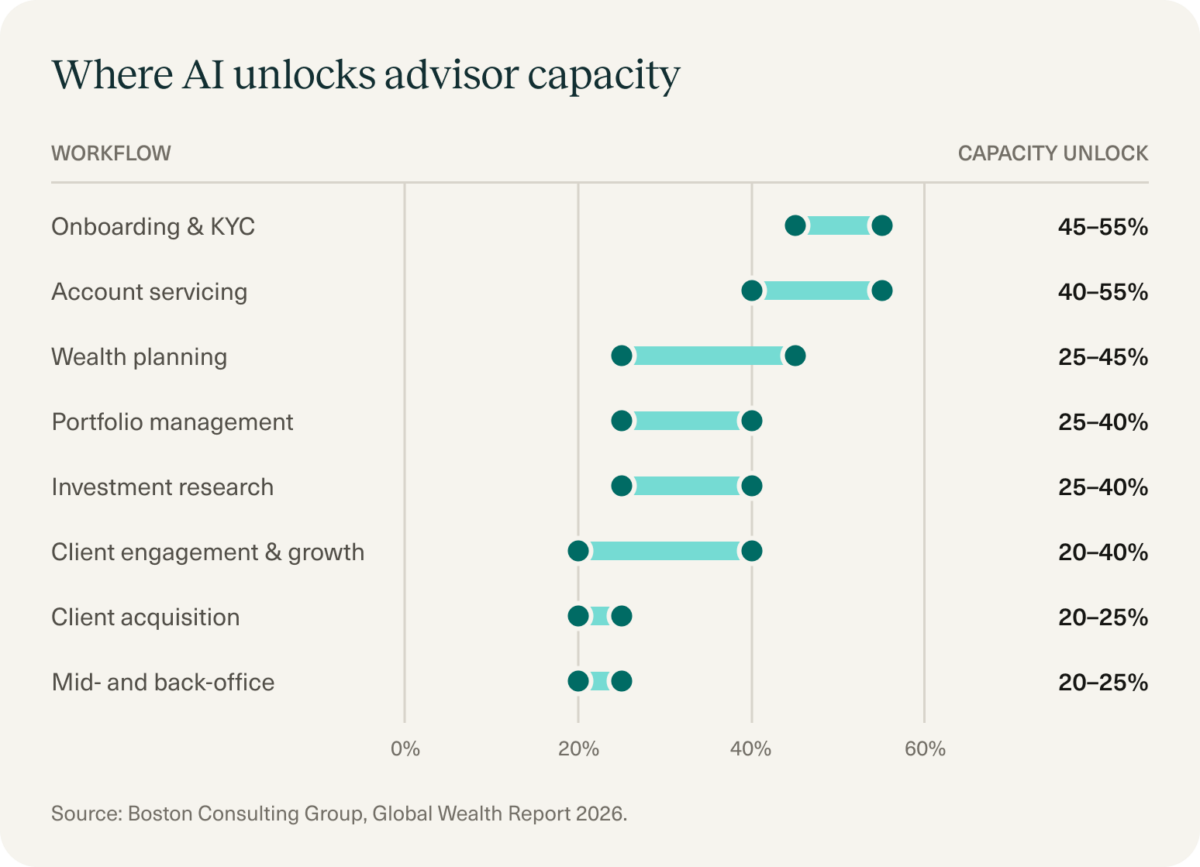
BCG estimates that AI could unlock significant capacity across nearly every major component of the wealth management value chain.
Those numbers raise a more consequential question than whether advisors are using AI:
There are two very different answers.
- A firm can use AI primarily to lower its cost to serve.
- Or it can use that same capacity to deliver more advice.
The second opportunity may ultimately be the more important one.
Imagine giving every advisor another day in the week
Consider what happens if technology meaningfully reduces the time advisors spend collecting information, preparing analysis, documenting meetings, servicing accounts and monitoring planning opportunities.
It is effectively the equivalent of giving advisors additional hours every week.
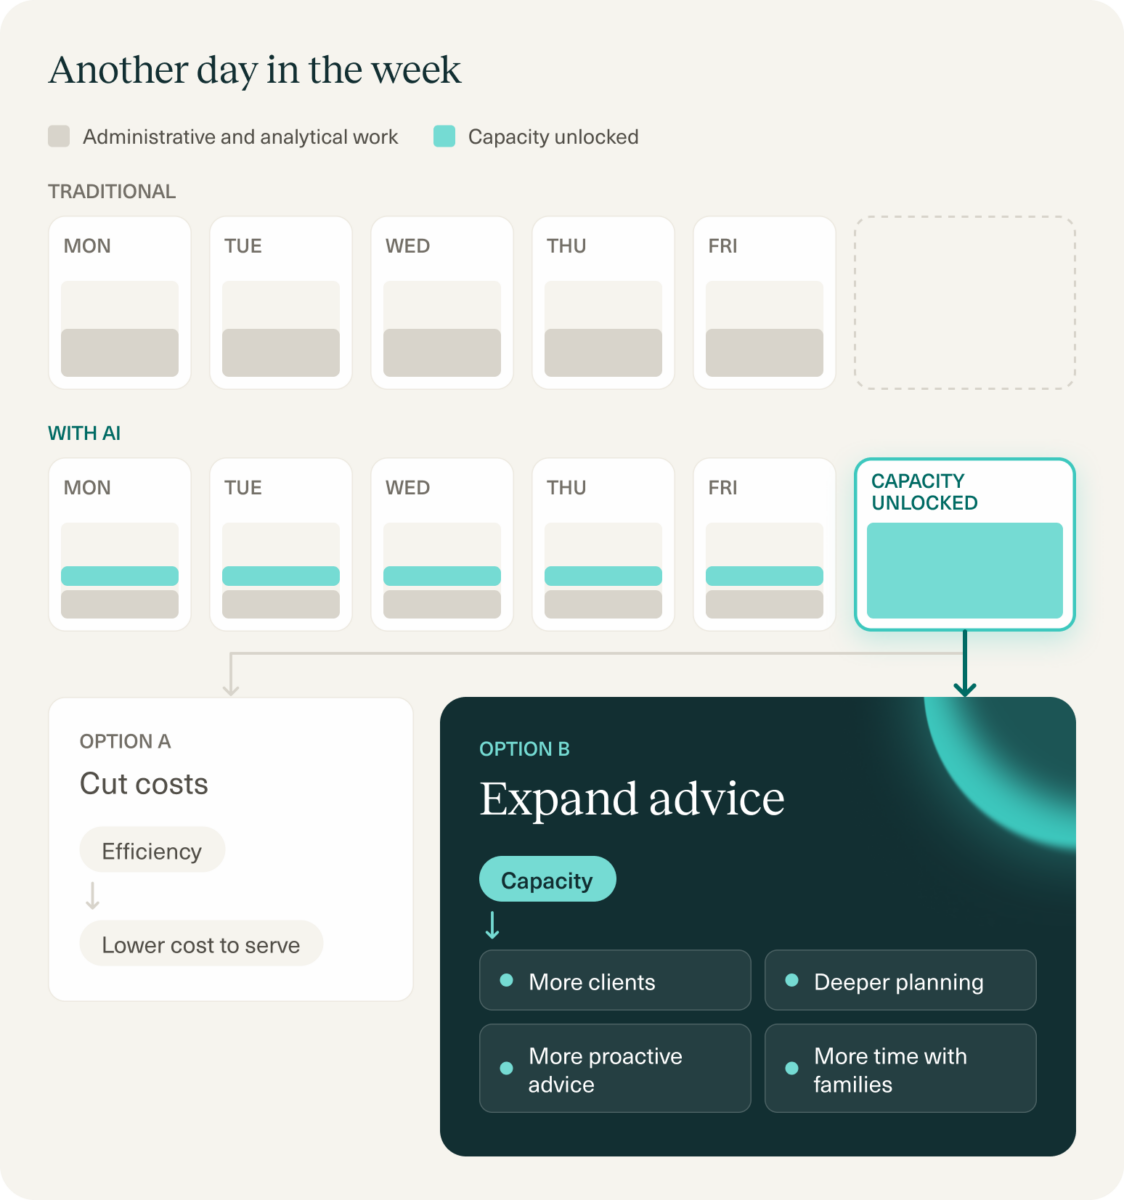
A firm could treat those hours as a cost-saving opportunity. Or it could reinvest them in the client relationship.
That could mean serving more households without sacrificing the client experience. It could mean going substantially deeper with existing clients. It could allow advisors to expand beyond traditional portfolio conversations into estate planning, tax planning, charitable strategies, business succession and multigenerational wealth planning.
It could also change the cadence of advice itself.
Historically, much of wealth management has been episodic. A client meets with an advisor periodically. Their circumstances are reviewed. Opportunities are identified. Recommendations follow.
An AI-enabled advisory model can become far more continuous.
Technology can help monitor a client’s financial life, identify relevant changes and surface potential planning opportunities between meetings. The advisor can spend less time searching for those opportunities and more time helping clients understand what they mean and what to do next.
That is a fundamentally different model of advice.
BCG reaches a similar conclusion. Rather than directing all AI-driven productivity gains toward cost reduction, the report argues that firms can deploy the capacity toward deeper relationships, higher-value services and clients who previously may not have been economical to serve.
In other words, the opportunity is not simply to make today’s wealth management model cheaper.
It is to make the model better.
AI can move the advisor up the value chain
There is an understandable fear that as AI becomes more capable, the role of the financial advisor becomes smaller.
For the best advisors, the opposite may be true.
As more repeatable work becomes automated, the value of uniquely human work increases.
BCG’s analysis draws a useful distinction. Activities such as document collection and processing, scenario generation, research synthesis, regulatory reporting, transaction monitoring and routine servicing are increasingly suited to AI augmentation or automation.
Meanwhile, life-stage coaching, multigenerational strategy, complex client requests and the trusted-advisor relationship remain substantially human-led.
That suggests the role of the advisor is not disappearing.
It is becoming more concentrated around the parts of advice that matter most.
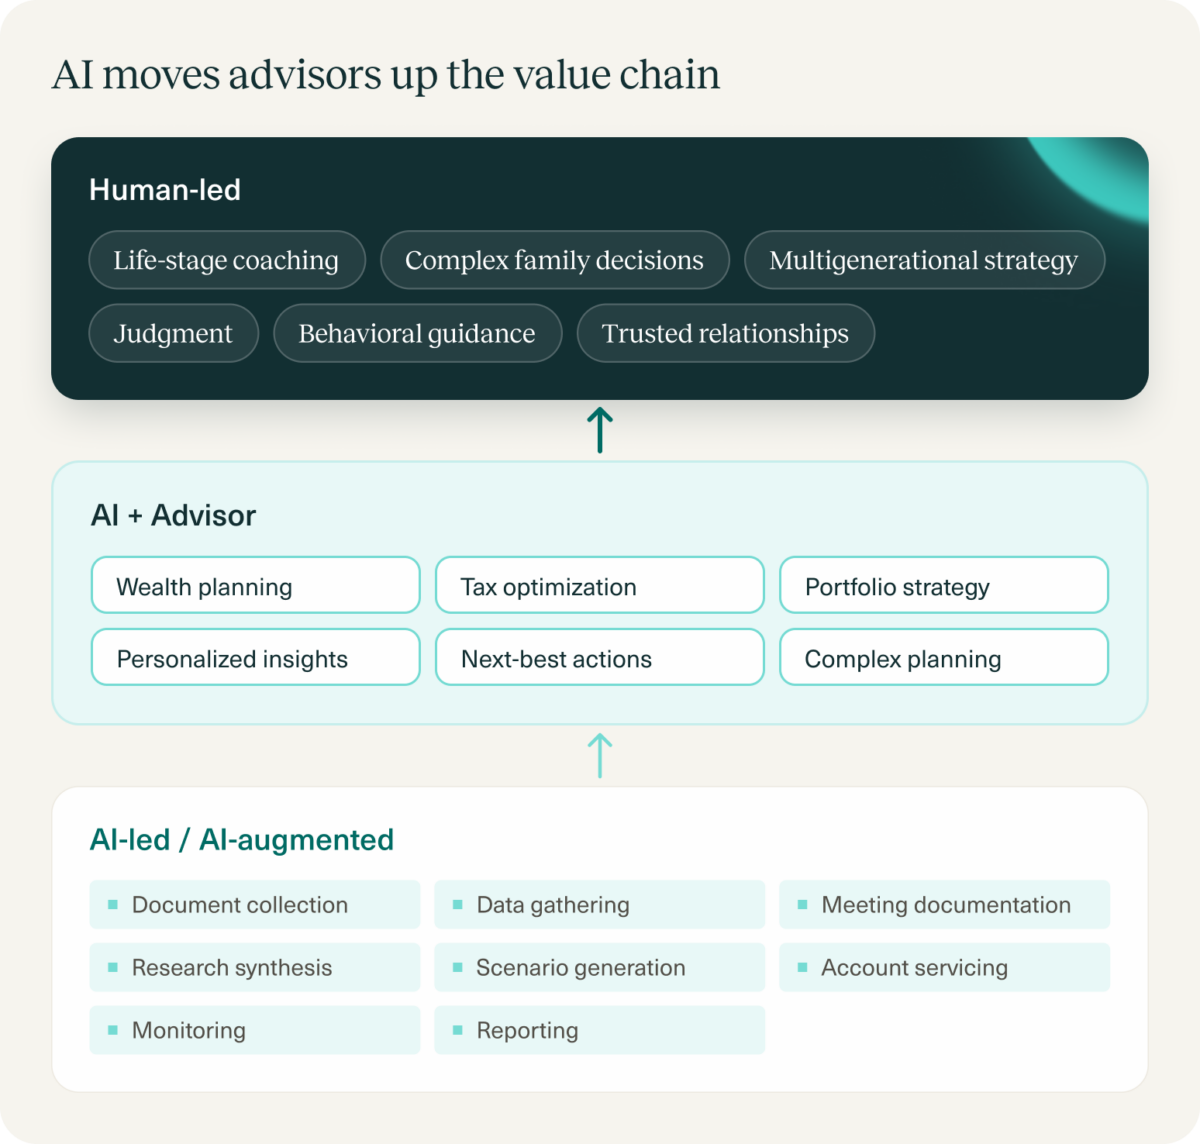
The advisor of the future may spend less time assembling the answer and more time helping a family understand what the answer means.
For decades, advisors have been asked to operate simultaneously as analysts, researchers, administrators, project managers, service representatives and relationship managers.
AI gives firms an opportunity to separate those responsibilities.
Technology can increasingly handle monitoring, synthesis and repeatable analysis. Advisors can devote more of their attention to judgment, communication, coaching and decision-making.
That is not a diminished role for the advisor.
It is a more valuable one.
Planning is where the economics become especially interesting
Nowhere is this shift more important than financial planning.
BCG identifies financial planning, portfolio management and compliance as both major cost pools and clear near-term opportunities for AI. Its recommendation to wealth managers is notably direct: move beyond experimentation and begin scaling AI across these workflows.
Estate and tax planning provide particularly useful examples of why the economics matter.
Both can deliver enormous value to clients, but they have historically been difficult to deliver broadly.
The work can require collecting significant amounts of information, understanding interconnected financial circumstances, analyzing documents, evaluating multiple scenarios and translating technical complexity into something a client can understand and act on.
That makes sophisticated planning expensive to deliver at scale.
As AI and modern planning technology compress the work surrounding those processes, the economics begin to change.
An advisor may be able to explore more scenarios. A firm may be able to deliver planning across a much larger portion of its client base. Planning opportunities that once required significant manual effort can increasingly be identified proactively.
The result could be a major expansion in access to sophisticated advice.
BCG points toward this possibility elsewhere in its report with what it calls the “Digital Multi-Family Office.” The model uses AI and modern infrastructure to extend capabilities traditionally associated with a multi-family office to clients with $1 million to $10 million in wealth at a fraction of the cost.
That idea has implications far beyond family offices.
AI can help push sophisticated planning further down the wealth spectrum while simultaneously allowing advisors serving high-net-worth families to go deeper.
That is not simply an efficiency gain. It is an expansion of what the industry can deliver.
But AI alone is not enough
The excitement around AI can sometimes create the impression that simply adding a large language model to an existing workflow makes a firm AI-first.
It does not.
BCG draws an important distinction between firms that layer AI onto existing processes and those that redesign workflows and processes around AI agents from the beginning. The report argues that the largest gains will accrue to organizations willing to rethink the operating model itself.
The difference can be substantial.
Adding AI to a ten-step process might make several steps faster.
Redesigning the workflow might eliminate seven of them.
That shift requires more than an AI assistant sitting beside the advisor. It requires connected data, modern infrastructure, integrated workflows and clear systems of control.
And in wealth management, it also requires recognizing that not every problem should be solved probabilistically.
That becomes particularly important in high-stakes areas such as estate and tax planning.
Generative AI can be extraordinarily powerful at interpreting information, surfacing opportunities and helping people navigate complexity. But planning also depends on accuracy, structured rules, reliable data, deterministic calculations and appropriate professional oversight.
BCG makes a similar architectural point in its recommendations for firms preparing for agentic workflows. AI agents need access to curated, real-time data, while their actions should remain governed by deterministic control layers such as transaction systems, rules engines and established workflows.
The most capable systems will not ask AI to do everything.
They will combine AI with purpose-built technology and deterministic systems so each component handles the work it is best suited to perform.
The real divide will be between AI-enabled and AI-first firms
Most wealth management firms will adopt AI.
That alone will not create a lasting competitive advantage.
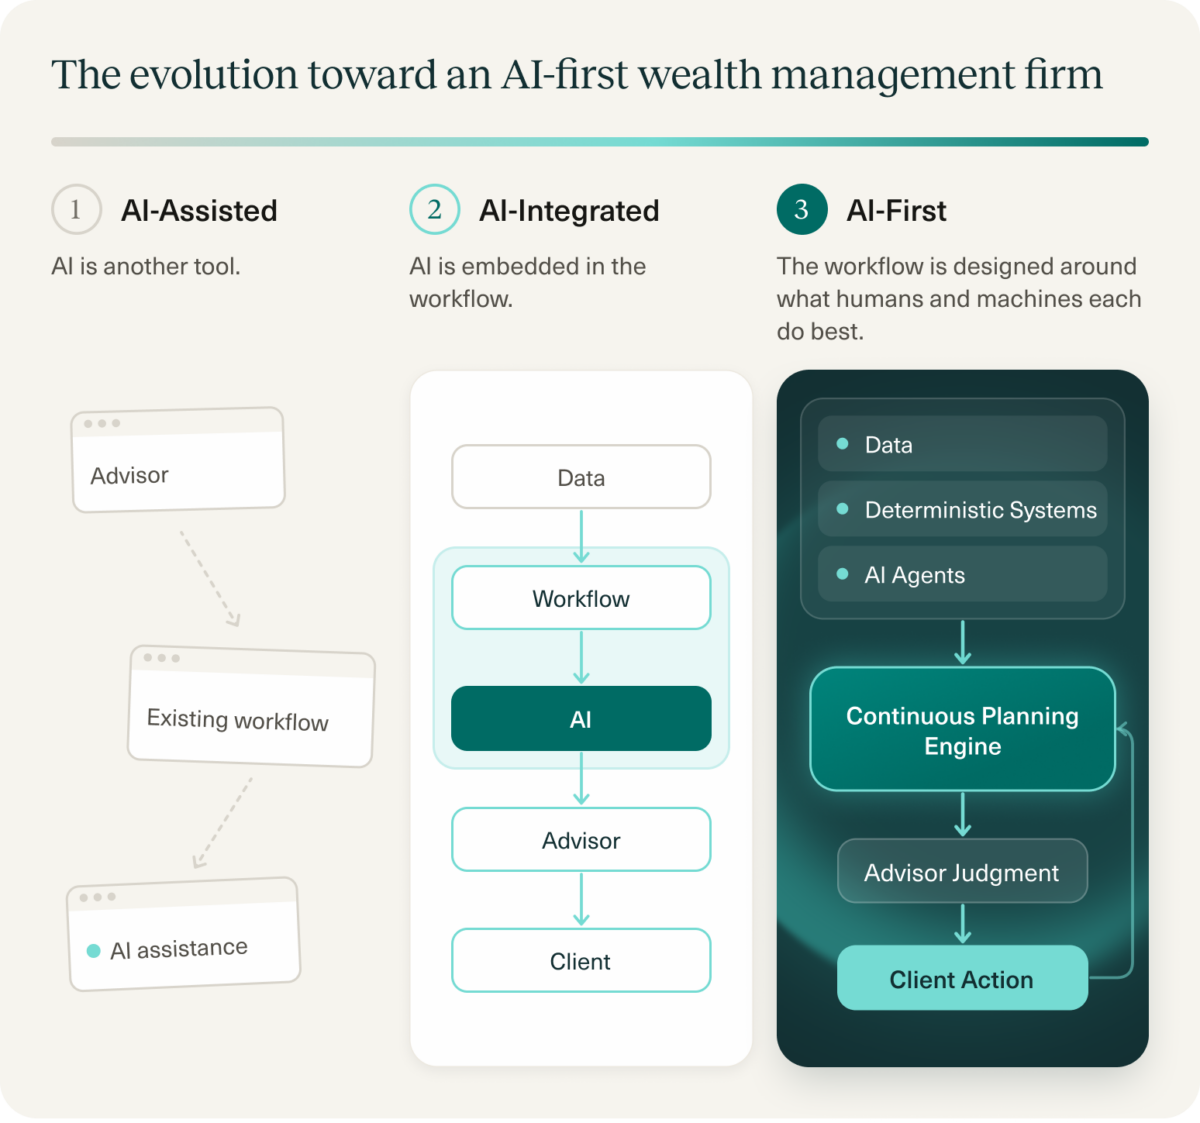
The larger divide will be between organizations that use AI to accelerate pieces of their current operating model and those that redesign the model itself.
An AI-assisted firm gives advisors new tools.
An AI-integrated firm embeds those tools throughout existing workflows.
An AI-first firm asks a more fundamental question:
That question leads somewhere very different.
The advisor’s workflow changes.
The client’s experience changes.
The number of clients an advisor can effectively serve changes.
The economics of sophisticated planning change.
And eventually, client expectations change too.
Once clients experience advice that is more proactive, more personalized and more responsive, periodic reviews and reactive planning begin to feel inadequate.
That may be one of the most important competitive consequences of AI.
The firms that move first do not simply become more efficient.
They begin resetting the standard for what advice looks like.
The ceiling on advice is moving
The wealth management industry has spent years debating whether AI will replace financial advisors.
That may be the wrong question.
The more useful question is what becomes possible when advisors no longer have to spend so much of their time doing work that technology can increasingly handle.
AI can make today’s wealth management model cheaper.
But that is the least ambitious version of the opportunity.
It can also allow advisors to serve more families, deliver more sophisticated planning, identify opportunities earlier and devote more of their time to the conversations in which human judgment matters most.
BCG ultimately sees disruption, rather than displacement, as the more likely outcome. In that future, AI expands capacity across the value chain and reshapes the economics of advice without removing its human core.
That future does not diminish the advisor.
It makes the advisor more valuable.
The first era of AI in wealth management was about productivity.
The next will be about capacity.
The firms that win will be the ones that decide carefully what to do with it.
At Wealth.com, we’re building for that future: one in which technology expands the reach and depth of sophisticated planning while giving advisors more time to do what technology cannot, understand their clients, guide consequential decisions and help families Plan for Every Tomorrow.
See how Wealth.com brings AI-powered estate and tax planning together to help advisors identify opportunities sooner, deliver sophisticated planning at scale and spend more time where their judgment matters most.