Your Client Has an Irrevocable Trust. Do They Actually Know What It Does?

A trust can be hundreds of pages long. It can involve multiple trustees, generations of beneficiaries, carefully drafted distribution standards, and sophisticated tax planning.

And yet, the person whose wealth it governs may still struggle to answer a basic question:

What actually happens under this trust if my life changes?

That question is getting a very public stress test in New Jersey.

Two Sigma co-founder John Overdeck and his estranged wife, Laura Overdeck, are in the midst of what Laura’s attorney has described as the largest contested divorce in New Jersey history. The couple married in 2002, after Two Sigma was founded in 2001, and the central issue in their divorce trial is whether John’s ownership interest in the investment firm is marital property. Laura is seeking a share of the stake that her attorney values at approximately $6.2 billion. John’s attorney disputes both her claim to the stake and that valuation, and has said John proposed $723 million in tax-free equitable distribution.

But another dispute surrounding the divorce raises an important issue for anyone involved in sophisticated estate planning.

In separate litigation, Laura alleges that she signed documents in 2018 that allowed assets to be moved from New Jersey trusts into new irrevocable trusts in Wyoming. According to her complaint, she believed the restructuring was primarily intended to produce tax benefits. She later alleged that the new trust provisions had consequences she did not understand, including removing her as a beneficiary if either spouse initiated divorce proceedings. The law firm involved has disputed her claims, and the litigation remains ongoing.

The courts will ultimately determine what happened, which assets were involved, what the parties understood, and whether anyone acted improperly.

For advisors, the more durable lesson has nothing to do with who wins.

A technically sophisticated estate plan is not necessarily a well-understood estate plan.

“Irrevocable” does not mean “nothing can ever change”

The word itself sounds permanent.

When clients hear irrevocable trust, many understandably assume the document has been locked, the assets are untouchable, and the terms can never change.

The reality is more nuanced.

An irrevocable trust generally cannot be freely revoked or amended by the person who created it in the same way a revocable living trust can. But irrevocable trusts come in many forms and can be designed for many different purposes. Their tax treatment, beneficiary rights, trustee powers, creditor protections, and flexibility depend heavily on the trust’s language and applicable law.

Even the tax consequences are not as simple as “irrevocable means outside the estate.” Depending on the powers or interests retained by a grantor, some or all trust property may still be included in the grantor’s estate for federal estate tax purposes.

And, under the right circumstances, certain irrevocable trusts can be modified, reformed, divided, merged, or even decanted.

Trust decanting generally involves exercising authority under applicable law and the governing instrument to move assets from an existing irrevocable trust into another trust with different terms. The Uniform Law Commission describes its Trust Decanting Act as a mechanism for reforming or modernizing an irrevocable trust, although the rules and availability vary by jurisdiction.

That flexibility can be enormously valuable.

A trust created decades ago may need to respond to changes in tax law, family circumstances, asset composition, state law, or a beneficiary’s needs.

But flexibility creates another responsibility: clients need to understand when the economics or consequences of their plan have changed, even if the documents still contain the word “irrevocable.”

The trust document is only part of the plan

Imagine an advisor reviewing a client’s balance sheet and seeing: Irrevocable Trust: $18,400,000

That tells you remarkably little.

  • Who created it?
  • Who funded it?
  • What assets are inside?
  • Who are the current beneficiaries?
  • Who are the remainder beneficiaries?
  • Who can make distributions?
  • Can the grantor replace the trustee?
  • Does a spouse have an interest?
  • What happens to that interest after divorce?
  • What happens if a child dies?
  • What happens if a beneficiary develops creditor problems?
  • Which state’s law governs the trust?
  • Are there powers of appointment?
  • Can the trust be modified or decanted?

For many families, those questions matter more than the trust’s current account value.

An irrevocable trust is not simply another container on the household balance sheet. It is a set of instructions for how ownership, control, access, and inheritance should work across time.

If the client cannot explain those instructions, there may be a gap between having an estate plan and understanding the estate plan.

Life events are where trust design gets tested

Estate planning often begins with a snapshot.

A married couple has three children. The business is worth $10 million. Everyone lives in the same state. The children are minors. The couple has certain tax exposures. Family relationships are stable.

Then life happens.

  • The business becomes worth $100 million.
  • A child gets married.
  • A beneficiary moves overseas.
  • A spouse dies.
  • Someone remarries.
  • Tax laws change.
  • A family moves from one state to another.
  • A beneficiary develops special needs.
  • A business is sold.
  • A marriage ends.

The trust may continue operating exactly as drafted while the family around it becomes completely different.

That is why sophisticated planning should not be treated as a one-time drafting exercise.

It should be periodically stress-tested against the lives clients are actually living today.

Jurisdiction matters, but it is not a substitute for good planning

The Overdeck litigation also puts a spotlight on the increasingly important role of trust jurisdiction.

Families are not always limited to establishing trusts in their home states. Depending on the circumstances, planners may consider jurisdictions with laws designed to support long-duration trusts, asset protection, trust administration, privacy, or favorable tax treatment.

Wyoming, for example, has enacted laws allowing qualified spendthrift trusts and has eliminated certain traditional limitations on the duration of noncharitable trusts.

These features can be useful planning tools. But a favorable jurisdiction should not be confused with a force field.

Changing the state governing a trust does not eliminate the need to understand how assets were transferred, who the beneficiaries are, what powers were granted, what duties trustees and other fiduciaries have, or how the structure interacts with other areas of law.

The more sophisticated the strategy becomes, the more important the explanation becomes with it.

Clients should understand consequences, not clauses

Most clients will never become trust and estate attorneys.

They should not have to.

The goal is not for a client to explain the finer points of discretionary distribution standards or recite provisions of a 90-page trust agreement.

They should understand the consequences.

An advisor reviewing an irrevocable trust with a client might start with questions such as:

  • Who benefits from this trust today?
  • Who controls investment and distribution decisions?
  • What can you still control, and what have you permanently given up?
  • Under what circumstances could you or your spouse stop being a beneficiary?
  • What happens when you die?
  • What happens when your spouse dies?
  • What changes if either of you remarries?
  • How are your children protected if they divorce?
  • Can future descendants become beneficiaries?
  • What happens if the trustee can no longer serve?
  • Which provisions can potentially be changed, and which cannot?
  • When was the last time this trust was reviewed against your current goals?

A client who can confidently answer those questions is in a very different planning position from a client who simply knows that “the attorneys set up a trust.”

Advisors can help close the understanding gap

Financial advisors are not substitutes for estate planning attorneys, nor should they be interpreting legal documents beyond the boundaries of their professional role.

But advisors are uniquely positioned to recognize when the legal architecture of a client’s estate no longer appears aligned with the rest of the financial picture.

They often see the changes first.

They know the business has appreciated dramatically.

They know a daughter is getting married.

They know the client moved from New York to Florida.

They know a spouse recently died.

They know the family sold a company.

They know an old trust has become one of the largest assets on the family’s balance sheet.

Those are opportunities to bring the client’s attorney, tax professional, and other specialists back into the conversation.

Technology can make that process easier by helping advisors move beyond simply cataloging that a trust exists. Modern estate planning tools can help surface ownership structures, beneficiaries, trustees, distribution provisions, and relationships across a family’s broader estate plan, making it easier to identify questions worth revisiting with counsel.

Because the question should not stop at: “Do you have an irrevocable trust?”

The better question is: “Does your client understand what that trust will actually do when life changes?”

Complexity should create clarity, not obscure it

The outcome of the Overdeck litigation is still unknown. Allegations remain disputed, and the courts will determine the legal and factual issues involved.

But advisors do not need to wait for a verdict to take something useful from the case.

Families are using increasingly sophisticated strategies to transfer wealth across generations, reduce taxes, protect beneficiaries, manage concentrated assets, and preserve family legacies.

That sophistication can be powerful.

It can also create distance between the documents clients sign and the outcomes they believe they are creating.

The best estate planning should do the opposite.

The more complex the structure, the clearer the client should be about what it means.

For advisors, that creates an opportunity to turn estate planning from a stack of documents into an ongoing planning conversation, one that evolves alongside the family it was designed to serve.


This material is provided for general informational and educational purposes only and should not be construed as legal, tax, or investment advice. The allegations discussed above remain subject to ongoing litigation.
Ester Is Now Available Through Schwab Advisor Center®

A client shares a trust, a will or a tax return. Inside those documents are details that could shape some of the most important financial decisions their family will make. For advisors, understanding those details and knowing which questions to ask can take significant time.

Ester helps advisors move that work forward.

Today at Schwab IMPACT®, Schwab announced that Ester, Wealth.com’s AI-powered tax and estate planning experience, is now available through Schwab Advisor Center.

Designed for RIAs who custody client assets with Schwab, the experience gives advisors a new way to review estate and tax documents, explore planning questions and prepare for more informed client conversations.

From complex documents to clearer planning conversations

Tax and estate planning documents tell an important story about a client’s intentions, financial circumstances and plans for the people they care about. Making that story easier to understand helps advisors play a more informed role in the planning relationship.

Advisors can open Ester from Schwab Advisor Center to:

  • Review estate and tax documents. Upload trusts, wills and tax returns, then ask questions about their contents.
  • Explore planning questions. Ask general tax and estate planning questions to support research and preparation.
  • Follow guided workflows. Produce structured reviews of potential risks, opportunities and planning considerations without starting from a blank prompt.
  • Make complex plans easier to discuss. Create visual summaries, including estate flowcharts and beneficiary maps, for advisor review and use in client conversations.

The goal is practical: help advisors understand what is in front of them, identify areas that warrant a closer look and have more productive conversations with clients.

“Advisors want to help clients navigate the decisions that matter most to their families, and tax and estate planning are central to those conversations,” said Tim White, Co-Founder & Chief Growth Officer at Wealth.com. “We’re excited to bring a focused experience powered by Ester into Schwab Advisor Center, helping advisors turn complex documents into clear insights and have deeper planning conversations. It also gives advisors a window into the broader capabilities of the Wealth.com platform, built to help them serve clients throughout the estate and tax planning process.”

A structured starting point, with the advisor in control

Advisors should not need to become prompt-writing experts to put AI to work.

Ester’s guided workflows give advisors a structured starting point for reviewing tax and estate planning information. They help organize the review so advisors do not have to know every question to ask before they begin.

Ester uses rules-based engines for core tax and estate calculations and draws legal and tax facts from verified sources. Its scope is limited to tax and estate planning.

Advisors review every output before acting on it. Ester provides planning information and decision support; it does not provide tax or legal advice.

How to access Ester in Schwab Advisor Center

Firm Security Administrators within eligible RIA firms have access today and can extend access to their teams through Firm Security Groups.

To begin, contact your Firm Security Administrator about enabling access, then open Ester from Schwab Advisor Center. Start with a guided workflow or a document you want to better understand.

Explore what comes next for your practice

Ester through Schwab Advisor Center is a powerful way to put Wealth.com’s planning intelligence to work.

For firms looking to support a broader planning process, the full Wealth.com platform brings together capabilities including estate document creation, scenario modeling, visualizations and client collaboration. The full platform is a separate paid offering, and advisors interested in its capabilities are eligible for an introductory offer.

Start with Ester through Schwab Advisor Center, or schedule a demo to explore the full Wealth.com platform and introductory offer.


Ester is provided by Wealth.com and is also available directly to RIAs. Schwab has been a minority investor in Wealth.com since April 2025. Availability is subject to firm eligibility and applicable terms. Outputs require advisor review. Ester does not provide tax or legal advice. Wealth.com is not a law firm and does not provide legal advice.

Schwab Advisor Center® is a website of Charles Schwab & Co., Inc. (Schwab) for the use of independent investment advisor clients that custody assets with Schwab.

The Great Wealth Transfer Begins with Women

At EstateCon 2026, four of the most influential leaders in wealth management took the stage with a unified conviction. Joanne Bradford, Strategic Advisor to Wealth.com; Kathie Chao, Managing Director at Charles Schwab; Kate Shackleton, Executive Managing Partner at Mercer Advisors; and Shannon Spotswood, CEO of RFG Advisory, made it clear: the Great Wealth Transfer will not just include women, it will be shaped and directed by them.

This article advances the insights shared on stage and translates them into strategic implications for your firm’s growth plans.

An estimated $124 trillion is expected to change hands over the next two decades. A significant share of that capital will be controlled by women through inheritance, divorce settlements, liquidity events, and rising earnings power.

For advisors, this is a structural shift from how the industry has traditionally operated, and it necessitates operational change and a shift in approach to client relationships.

If your firm intends to lead during the Great Wealth Transfer, the following seven insights outline how firms can position themselves to serve women in wealth with clarity and purpose.

1. The Center of Gravity Is Shifting

The Great Wealth Transfer is frequently described as an intergenerational event, but its immediate impact is not necessarily limited to parents and their children.

Women are projected to control over $30 trillion in assets by the end of this decade. At the same time, younger cohorts of women are investing earlier and engaging more actively in financial decision-making than prior generations.

This shift requires more than revised marketing language. It requires acknowledging that women in wealth are not peripheral beneficiaries of capital transitions.

They are the primary decision-makers, business owners, executives, and wealth creators. In fact, in more than two-thirds of households in the United States today, women are the ones making the primary decisions when it comes to investing.

If an advisory firm treats women as a secondary initiative, it will struggle to compete with firms that recognize women clients in the primary position that they deserve.

2. The Retention Gap Is a Risk to Firm Growth

Industry data shows that as many as 80% of widows leave their financial advisor within a year of their spouse’s death. Divorce produces similar patterns of attrition.

When so much money is in motion, retention failure becomes a material economic risk to the continued growth of an advisory firm.

Many women report feeling overlooked in meetings with their advisor, excluded from technical discussions, or addressed through their spouse rather than as an equal participant. Jargon-heavy communication reinforces distance rather than trust.

For advisors, the implication is easy to understand. Engagement must be intentional, inclusive, and designed for both spouses from the outset. Modern estate planning offers one of the most effective entry points to get that alignment correct.

3. Education Builds Agency

Research consistently shows that a majority of women—eighty-five percent—wish they had begun investing earlier. That regret reflects a lack of access to clear, practical financial education delivered at the right moment, not a lack of ability.

Women often approach financial decisions through scenario modeling. Questions such as “When can I retire?” or “How would a move affect our plan?” reflect a desire to understand trade-offs and future outcomes. Purpose-driven financial advice can meet that need by connecting technical planning to clearly defined life goals and long-term outcomes.

Modern estate planning supports this framework by visualizing asset flow, beneficiary structures, and long-term impact in ways that are accessible without oversimplifying complexity.

4. Estate Planning Is a Strategic Engagement Tool

Many advisors may have begun their career focused on investment management, but today’s focus on more comprehensive financial guidance means that estate planning can often create the most inclusive conversation.

Estate planning brings both spouses into the discussion, introduces next-generation heirs, and surfaces values that extend far beyond portfolio allocation or retirement planning.

When estate planning is paper-heavy, attorney-centric, and disconnected from the broader advisory workflow, it reinforces friction. When it is delivered through a secure, digital, advisor-first platform, it easily becomes a collaborative process that strengthens the client-advisor relationship.

The Great Wealth Transfer will reward firms that treat modern estate planning as a strategic growth lever rather than a compliance exercise. Advisors who integrate estate, tax, and financial planning into a comprehensive client experience will be positioned to retain more assets across transitions.

5. Women Are a Business Segment

Serving women in wealth requires deliberate strategy. You cannot reduce your plan to hosting a single event or assigning a female advisor to cover relationships.

Firms that succeed in this space treat women as a defined buying segment with particular priorities, specific communication preferences, and differentiated life stages.

Here’s what you can do to be more effective. Train your advisors to conduct needs-based conversations, design events that address financial stress felt more intimately by women, and align your marketing outreach to resonate with the real-world concerns expressed by women.

Firms should also systematically gather feedback from the women they already serve and incorporate those insights into their practice design and communication strategy.

It has been studied and known for decades that women refer business to their advisors at higher rates than men. In the context of the Great Wealth Transfer, that referral dynamic has the potential to further compound growth as your firm works with more women.

6. Digital Expectations Have Evolved

The trend of clients increasingly looking outside their advisor for answers is only growing with the evolution of AI.

Today’s clients can model retirement scenarios, research estate structures, and consult Google or AI to explore nuanced and sophisticated financial outcomes, all without the help of their advisor.

These behaviors aren’t replacing their advisor, but they are reshaping expectations about access, responsiveness, and the digital client experience.

When it comes to women, who are more likely to balance professional and family responsibilities, engaging with financial content outside traditional hours can be the norm.

An advisory model limited to quarterly reviews and PDF or paper documents does not align with that reality. Modern estate planning has to be accessible, secure, and designed for ongoing collaboration.

Is your technology doing its part to reduce friction with document review, beneficiary updates, and collaboration? Integrating better estate technology into your advisor workflow before clients, especially women, start to push back on a lack of flexibility can help you get ahead of the conversation.

7. Operational Excellence Determines Outcomes

It’s time to clear up operational fragmentation within your firm. Advisors who spend a majority of their day on manual processes, working within disconnected systems, or spending time on non-revenue-generating tasks will struggle to scale their advice and relationships.

Women in wealth increasingly expect integrated planning across investments, taxes, and estate strategy. Delivering purpose-driven financial advice at scale requires a well-run firm supported by secure, integrated technology.

Firms that professionalize their operations, invest in training, and adopt comprehensive platforms will be able to focus on their core superpower: building trust.

Advancing the Conversation with Wealth.com

The EstateCon panel made clear that the Great Wealth Transfer begins with women. The next step for advisors is to translate that insight into structural change. Engaging women intentionally, modernizing estate planning delivery, and committing to operational excellence are strategic imperatives.

Our platform was built to support this moment. By modernizing how estate plans are created, visualized, and maintained, you can deliver the clarity and confidence that your clients expect, no matter their gender.

Why Single-Tenant Architecture Matters for Modern Wealth Management Firms

A bank and an independent advisory firm may use estate and tax planning technology to help clients answer many of the same questions. How will their wealth transfer? How do their estate documents fit together? What planning opportunities deserve attention?

But the environments in which that technology must operate can look very different.

For an advisory firm, the priority may be bringing sophisticated planning into everyday client conversations through a secure, dependable platform. A large financial institution needs those same capabilities, but may also have specific requirements around infrastructure isolation, vendor risk, integrations, resource allocation and change management.

That is where single-tenant architecture becomes relevant.

The vast majority of Wealth.com customers use our multi-tenant environment. For most firms, that is the appropriate deployment model. For institutions with additional infrastructure and operating requirements, Wealth.com also offers a dedicated, single-tenant environment.

What does single-tenant architecture mean?

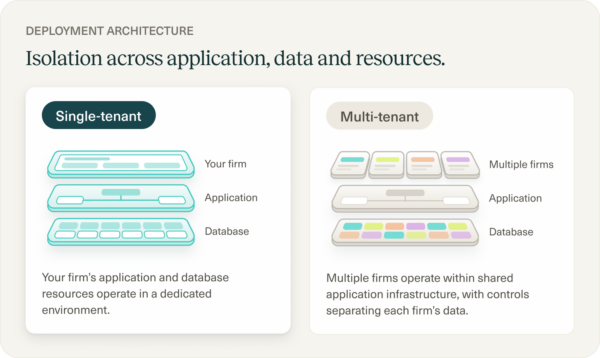
Diagram comparing single-tenant and multi-tenant deployment architecture.

Tenancy describes how a software platform’s application environment and supporting resources are organized across customers.

In a multi-tenant environment, multiple firms operate within shared application infrastructure, with controls separating each firm’s data.

In a single-tenant environment, one firm’s application and database resources operate within a dedicated environment. Wealth.com’s single-tenant deployment also includes isolated compute resources and firm-specific security controls across networking, encryption, identity and monitoring.

The important distinction is that sharing infrastructure is not the same as sharing access to information. A multi-tenant deployment uses controls to maintain separation between firms within the shared environment. Single tenancy changes how that separation is implemented and how the environment can be configured and operated for an individual institution.

Why institutional requirements can be different

A family’s estate and tax information deserves protection whether its advisor works at an independent RIA or a national bank.

What changes is not the importance of the information. It is the organizational environment surrounding it.

For a large financial institution, evaluating a planning platform may involve questions that extend well beyond the advisor experience. Which application and database resources are dedicated to the institution? How are access and monitoring scoped? Can integrations accommodate the institution’s systems? How will changes be coordinated?

These are questions about how technology fits within an operating model.

One useful way to think about single tenancy is to ask where the application, data and resource boundaries sit. Wealth.com’s dedicated deployment establishes those boundaries around an individual firm’s application and database environment, with firm-specific controls supporting assessment and oversight.

That can be valuable when an institution needs a more specifically scoped environment rather than additional functionality in the software itself.

At institutional scale, how a platform is deployed can matter alongside what it enables advisors to do.

Three reasons institutions may choose a dedicated environment

The value of single tenancy becomes clearer when translated from architecture into the work technology and security teams need to perform.

1. A defined environment for security oversight and vendor risk

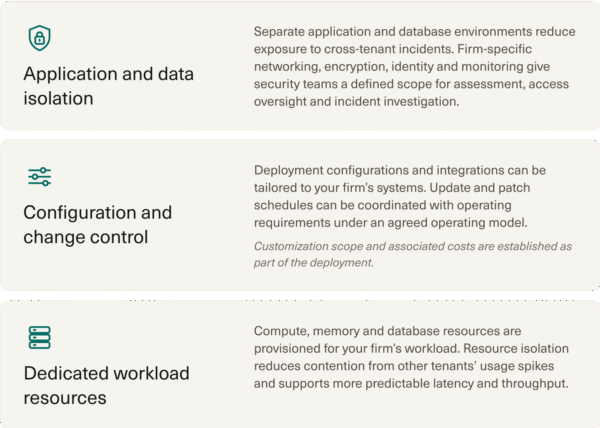
Separate application and database environments reduce exposure to cross-tenant incidents. Firm-specific networking, encryption, identity and monitoring also give security teams a defined scope for assessment, access oversight and incident investigation.

For an institution evaluating a planning platform, that scope matters. It helps focus the review on the environment supporting its own deployment: the relevant application, database, resources and controls.

Wealth.com’s single-tenant offering is designed to reduce cross-tenant dependencies and provide a clearly scoped environment for vendor-risk assessment.

The benefit is not a promise that risk disappears. It is a more defined deployment boundary within which the institution and its technology provider can assess and manage it.

2. Configuration and change management aligned with the institution

The value of enterprise software depends partly on how well it fits the systems and processes already in place.

Consider an institution introducing a planning platform alongside its existing technology. The evaluation may include not only whether an integration is available, but how it will be configured and how subsequent changes will be coordinated with operations.

Wealth.com’s single-tenant deployment allows configurations and integrations to be tailored to a firm’s systems. Update and patch schedules can also be coordinated with operating requirements under an agreed operating model. Customization scope and associated costs are established as part of the deployment.

This is a practical distinction. The value is not unlimited customization or unrestricted control over updates. It is the ability to establish an agreed approach to configuration and change that reflects the institution’s requirements.

For a bank or large wealth management organization, that alignment can be an important part of making a platform workable across the enterprise.

3. Resources provisioned for the firm’s workload

Single tenancy also changes how resources are allocated.

In Wealth.com’s dedicated environment, compute, memory and database resources are provisioned for the firm’s workload. Resource isolation reduces contention from other tenants’ usage spikes and supports more predictable latency and throughput.

For an institution assessing a broad deployment, this provides a concrete topic for capacity planning: what resources its workload requires and how those resources will be provisioned.

Estate and tax planning deserve a place in the infrastructure conversation

Estate and tax planning involve more than a set of calculations or reports. They bring sensitive information about a family’s finances, documents and relationships into the planning process.

Wealth.com’s single-tenant deployment is designed to establish a defined environment for that estate, tax and family information.

For an institution considering how to deliver planning across its organization, the evaluation should therefore address both sides of the decision.

The wealth management team needs to understand how the platform will support advisors and clients. The technology and security teams need to understand how the deployment will fit the institution’s requirements.

Those conversations should inform one another. A strong advisor experience does not remove the need for infrastructure diligence, and a well-defined deployment does not replace the need for useful planning capabilities.

Institutions should be able to evaluate both without treating one as an afterthought.

Does every wealth management firm need single tenancy? No.

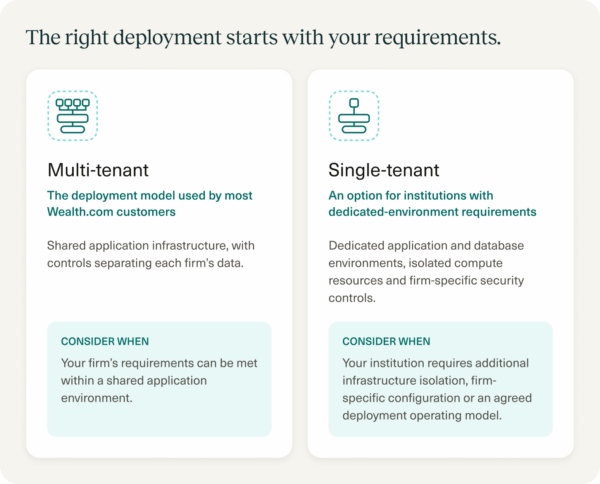
Comparison of deployment models for wealth management firms.

Single tenancy is not a required next step for every growing advisory firm.

The vast majority of Wealth.com customers operate in our multi-tenant environment. Choosing that deployment does not mean a firm places less importance on security or that its clients’ information deserves less protection.

It means a dedicated application and database environment may not be necessary to meet that firm’s requirements.

There is also an investment associated with operating a separate deployment. Wealth.com’s single-tenant offering supports dedicated application and database environments, firm-specific networking and encryption, dedicated identity and monitoring, environment provisioning and ongoing operational support.

Those resources and operating arrangements should serve a defined need.

For most advisory firms, the decision will not turn on whether dedicated infrastructure sounds more sophisticated. It should turn on whether their requirements call for that infrastructure and the associated operating model.

The same principle applies to large organizations. Size alone should not decide the architecture. The institution’s requirements should.

What institutions should ask planning technology providers

A useful evaluation moves beyond asking whether a provider offers single tenancy. It examines what the offering actually includes and how it will operate.

Five questions provide a starting point:

  1. What is dedicated, and what remains shared? Ask the provider to identify the application, database and workload resources within the dedicated environment, along with any remaining dependencies.
  2. How are security controls scoped to our institution? Review the approach to networking, encryption, identity, monitoring and access oversight, including the scope available for incident investigation.
  3. What can be configured, and under what terms? Clarify integration options, customization boundaries, associated costs and responsibility for ongoing support.
  4. How will updates be coordinated? Establish the operating model for change scheduling rather than assuming that a dedicated environment gives the institution unrestricted control.
  5. What investment and operational support does the deployment require? Understand how resources will be provisioned, how the environment will be supported and how the arrangement fits the institution’s vendor-risk assessment.

The answers matter more than the label. They turn “single tenant” from an architectural description into a deployment an institution can evaluate.

Built for independent firms and institutional requirements

Wealth.com’s approach is to support different deployment needs without making every customer adopt the same infrastructure model.

For most customers, that means using our multi-tenant environment to bring estate and tax planning into the advisory relationship.

For institutions requiring a dedicated deployment, it means separate application and database environments, isolated compute resources, firm-specific security controls and an agreed approach to configuration, change management and operational support.

Wealth.com is the only estate and tax planning provider to offer single-tenant capabilities. Our enterprise experience also includes successful deployments at three of the top five U.S. banks.

Our philosophy is straightforward: an independent advisory firm should not need a bank’s deployment model to deliver sophisticated planning. A bank should not have to set aside its institutional requirements to access the same planning capabilities.

The right technology partner should understand both.

Enterprise planning is about what the software enables. At institutional scale, it is also about how that software fits the organization.

Explore Wealth.com for Enterprise

Talk with our team about your institution’s estate and tax planning needs, deployment requirements and operating model. Learn more at https://www.wealth.com/for-enterprises/.

1 2 3 … 13