Your Client Has an Irrevocable Trust. Do They Actually Know What It Does?

A trust can be hundreds of pages long. It can involve multiple trustees, generations of beneficiaries, carefully drafted distribution standards, and sophisticated tax planning.

And yet, the person whose wealth it governs may still struggle to answer a basic question:

What actually happens under this trust if my life changes?

That question is getting a very public stress test in New Jersey.

Two Sigma co-founder John Overdeck and his estranged wife, Laura Overdeck, are in the midst of what Laura’s attorney has described as the largest contested divorce in New Jersey history. The couple married in 2002, after Two Sigma was founded in 2001, and the central issue in their divorce trial is whether John’s ownership interest in the investment firm is marital property. Laura is seeking a share of the stake that her attorney values at approximately $6.2 billion. John’s attorney disputes both her claim to the stake and that valuation, and has said John proposed $723 million in tax-free equitable distribution.

But another dispute surrounding the divorce raises an important issue for anyone involved in sophisticated estate planning.

In separate litigation, Laura alleges that she signed documents in 2018 that allowed assets to be moved from New Jersey trusts into new irrevocable trusts in Wyoming. According to her complaint, she believed the restructuring was primarily intended to produce tax benefits. She later alleged that the new trust provisions had consequences she did not understand, including removing her as a beneficiary if either spouse initiated divorce proceedings. The law firm involved has disputed her claims, and the litigation remains ongoing.

The courts will ultimately determine what happened, which assets were involved, what the parties understood, and whether anyone acted improperly.

For advisors, the more durable lesson has nothing to do with who wins.

A technically sophisticated estate plan is not necessarily a well-understood estate plan.

“Irrevocable” does not mean “nothing can ever change”

The word itself sounds permanent.

When clients hear irrevocable trust, many understandably assume the document has been locked, the assets are untouchable, and the terms can never change.

The reality is more nuanced.

An irrevocable trust generally cannot be freely revoked or amended by the person who created it in the same way a revocable living trust can. But irrevocable trusts come in many forms and can be designed for many different purposes. Their tax treatment, beneficiary rights, trustee powers, creditor protections, and flexibility depend heavily on the trust’s language and applicable law.

Even the tax consequences are not as simple as “irrevocable means outside the estate.” Depending on the powers or interests retained by a grantor, some or all trust property may still be included in the grantor’s estate for federal estate tax purposes.

And, under the right circumstances, certain irrevocable trusts can be modified, reformed, divided, merged, or even decanted.

Trust decanting generally involves exercising authority under applicable law and the governing instrument to move assets from an existing irrevocable trust into another trust with different terms. The Uniform Law Commission describes its Trust Decanting Act as a mechanism for reforming or modernizing an irrevocable trust, although the rules and availability vary by jurisdiction.

That flexibility can be enormously valuable.

A trust created decades ago may need to respond to changes in tax law, family circumstances, asset composition, state law, or a beneficiary’s needs.

But flexibility creates another responsibility: clients need to understand when the economics or consequences of their plan have changed, even if the documents still contain the word “irrevocable.”

The trust document is only part of the plan

Imagine an advisor reviewing a client’s balance sheet and seeing: Irrevocable Trust: $18,400,000

That tells you remarkably little.

  • Who created it?
  • Who funded it?
  • What assets are inside?
  • Who are the current beneficiaries?
  • Who are the remainder beneficiaries?
  • Who can make distributions?
  • Can the grantor replace the trustee?
  • Does a spouse have an interest?
  • What happens to that interest after divorce?
  • What happens if a child dies?
  • What happens if a beneficiary develops creditor problems?
  • Which state’s law governs the trust?
  • Are there powers of appointment?
  • Can the trust be modified or decanted?

For many families, those questions matter more than the trust’s current account value.

An irrevocable trust is not simply another container on the household balance sheet. It is a set of instructions for how ownership, control, access, and inheritance should work across time.

If the client cannot explain those instructions, there may be a gap between having an estate plan and understanding the estate plan.

Life events are where trust design gets tested

Estate planning often begins with a snapshot.

A married couple has three children. The business is worth $10 million. Everyone lives in the same state. The children are minors. The couple has certain tax exposures. Family relationships are stable.

Then life happens.

  • The business becomes worth $100 million.
  • A child gets married.
  • A beneficiary moves overseas.
  • A spouse dies.
  • Someone remarries.
  • Tax laws change.
  • A family moves from one state to another.
  • A beneficiary develops special needs.
  • A business is sold.
  • A marriage ends.

The trust may continue operating exactly as drafted while the family around it becomes completely different.

That is why sophisticated planning should not be treated as a one-time drafting exercise.

It should be periodically stress-tested against the lives clients are actually living today.

Jurisdiction matters, but it is not a substitute for good planning

The Overdeck litigation also puts a spotlight on the increasingly important role of trust jurisdiction.

Families are not always limited to establishing trusts in their home states. Depending on the circumstances, planners may consider jurisdictions with laws designed to support long-duration trusts, asset protection, trust administration, privacy, or favorable tax treatment.

Wyoming, for example, has enacted laws allowing qualified spendthrift trusts and has eliminated certain traditional limitations on the duration of noncharitable trusts.

These features can be useful planning tools. But a favorable jurisdiction should not be confused with a force field.

Changing the state governing a trust does not eliminate the need to understand how assets were transferred, who the beneficiaries are, what powers were granted, what duties trustees and other fiduciaries have, or how the structure interacts with other areas of law.

The more sophisticated the strategy becomes, the more important the explanation becomes with it.

Clients should understand consequences, not clauses

Most clients will never become trust and estate attorneys.

They should not have to.

The goal is not for a client to explain the finer points of discretionary distribution standards or recite provisions of a 90-page trust agreement.

They should understand the consequences.

An advisor reviewing an irrevocable trust with a client might start with questions such as:

  • Who benefits from this trust today?
  • Who controls investment and distribution decisions?
  • What can you still control, and what have you permanently given up?
  • Under what circumstances could you or your spouse stop being a beneficiary?
  • What happens when you die?
  • What happens when your spouse dies?
  • What changes if either of you remarries?
  • How are your children protected if they divorce?
  • Can future descendants become beneficiaries?
  • What happens if the trustee can no longer serve?
  • Which provisions can potentially be changed, and which cannot?
  • When was the last time this trust was reviewed against your current goals?

A client who can confidently answer those questions is in a very different planning position from a client who simply knows that “the attorneys set up a trust.”

Advisors can help close the understanding gap

Financial advisors are not substitutes for estate planning attorneys, nor should they be interpreting legal documents beyond the boundaries of their professional role.

But advisors are uniquely positioned to recognize when the legal architecture of a client’s estate no longer appears aligned with the rest of the financial picture.

They often see the changes first.

They know the business has appreciated dramatically.

They know a daughter is getting married.

They know the client moved from New York to Florida.

They know a spouse recently died.

They know the family sold a company.

They know an old trust has become one of the largest assets on the family’s balance sheet.

Those are opportunities to bring the client’s attorney, tax professional, and other specialists back into the conversation.

Technology can make that process easier by helping advisors move beyond simply cataloging that a trust exists. Modern estate planning tools can help surface ownership structures, beneficiaries, trustees, distribution provisions, and relationships across a family’s broader estate plan, making it easier to identify questions worth revisiting with counsel.

Because the question should not stop at: “Do you have an irrevocable trust?”

The better question is: “Does your client understand what that trust will actually do when life changes?”

Complexity should create clarity, not obscure it

The outcome of the Overdeck litigation is still unknown. Allegations remain disputed, and the courts will determine the legal and factual issues involved.

But advisors do not need to wait for a verdict to take something useful from the case.

Families are using increasingly sophisticated strategies to transfer wealth across generations, reduce taxes, protect beneficiaries, manage concentrated assets, and preserve family legacies.

That sophistication can be powerful.

It can also create distance between the documents clients sign and the outcomes they believe they are creating.

The best estate planning should do the opposite.

The more complex the structure, the clearer the client should be about what it means.

For advisors, that creates an opportunity to turn estate planning from a stack of documents into an ongoing planning conversation, one that evolves alongside the family it was designed to serve.


This material is provided for general informational and educational purposes only and should not be construed as legal, tax, or investment advice. The allegations discussed above remain subject to ongoing litigation.
Ester Is Now Available Through Schwab Advisor Center®

A client shares a trust, a will or a tax return. Inside those documents are details that could shape some of the most important financial decisions their family will make. For advisors, understanding those details and knowing which questions to ask can take significant time.

Ester helps advisors move that work forward.

Today at Schwab IMPACT®, Schwab announced that Ester, Wealth.com’s AI-powered tax and estate planning experience, is now available through Schwab Advisor Center.

Designed for RIAs who custody client assets with Schwab, the experience gives advisors a new way to review estate and tax documents, explore planning questions and prepare for more informed client conversations.

From complex documents to clearer planning conversations

Tax and estate planning documents tell an important story about a client’s intentions, financial circumstances and plans for the people they care about. Making that story easier to understand helps advisors play a more informed role in the planning relationship.

Advisors can open Ester from Schwab Advisor Center to:

  • Review estate and tax documents. Upload trusts, wills and tax returns, then ask questions about their contents.
  • Explore planning questions. Ask general tax and estate planning questions to support research and preparation.
  • Follow guided workflows. Produce structured reviews of potential risks, opportunities and planning considerations without starting from a blank prompt.
  • Make complex plans easier to discuss. Create visual summaries, including estate flowcharts and beneficiary maps, for advisor review and use in client conversations.

The goal is practical: help advisors understand what is in front of them, identify areas that warrant a closer look and have more productive conversations with clients.

“Advisors want to help clients navigate the decisions that matter most to their families, and tax and estate planning are central to those conversations,” said Tim White, Co-Founder & Chief Growth Officer at Wealth.com. “We’re excited to bring a focused experience powered by Ester into Schwab Advisor Center, helping advisors turn complex documents into clear insights and have deeper planning conversations. It also gives advisors a window into the broader capabilities of the Wealth.com platform, built to help them serve clients throughout the estate and tax planning process.”

A structured starting point, with the advisor in control

Advisors should not need to become prompt-writing experts to put AI to work.

Ester’s guided workflows give advisors a structured starting point for reviewing tax and estate planning information. They help organize the review so advisors do not have to know every question to ask before they begin.

Ester uses rules-based engines for core tax and estate calculations and draws legal and tax facts from verified sources. Its scope is limited to tax and estate planning.

Advisors review every output before acting on it. Ester provides planning information and decision support; it does not provide tax or legal advice.

How to access Ester in Schwab Advisor Center

Firm Security Administrators within eligible RIA firms have access today and can extend access to their teams through Firm Security Groups.

To begin, contact your Firm Security Administrator about enabling access, then open Ester from Schwab Advisor Center. Start with a guided workflow or a document you want to better understand.

Explore what comes next for your practice

Ester through Schwab Advisor Center is a powerful way to put Wealth.com’s planning intelligence to work.

For firms looking to support a broader planning process, the full Wealth.com platform brings together capabilities including estate document creation, scenario modeling, visualizations and client collaboration. The full platform is a separate paid offering, and advisors interested in its capabilities are eligible for an introductory offer.

Start with Ester through Schwab Advisor Center, or schedule a demo to explore the full Wealth.com platform and introductory offer.


Ester is provided by Wealth.com and is also available directly to RIAs. Schwab has been a minority investor in Wealth.com since April 2025. Availability is subject to firm eligibility and applicable terms. Outputs require advisor review. Ester does not provide tax or legal advice. Wealth.com is not a law firm and does not provide legal advice.

Schwab Advisor Center® is a website of Charles Schwab & Co., Inc. (Schwab) for the use of independent investment advisor clients that custody assets with Schwab.

How Advisors Use Tax Software to Deliver Personalized Planning at Scale

For your clients, personalized tax planning is an expectation.

And as a financial advisor, you know that tax strategies should reflect each client’s income sources, residency, business ownership, and long-term goals.

But delivering truly customized guidance across hundreds of households creates operational inefficiency as clients ask for more precision and accountability.

This gap creates a missed opportunity, especially if you consider how closely linked taxes and estate planning should be.

Tax planning and estate planning are inseparable components of a complete financial plan, but the industry has historically treated them as disconnected disciplines. The result is advice that optimizes for moments-in-time instead of compounding value across years.

The Wealth.com Tax Planning tools change that dynamic.

By integrating tax and estate planning with intelligent automation, advisors can move beyond calculating a tax bill and toward architecting a client’s future.

Here’s how your firm can deliver personalized tax planning at scale with these tools.

The Personalization Problem in Tax Planning

No two tax situations are ever alike. Situations between clients differ across income sources, state residency, equity compensation, business ownership, charitable preferences, and family structure. Even within the same household, small changes in the life of one person can materially alter planning outcomes for an entire family.

Traditional tax planning workflows are not built for this level of variation.

Advisors rely on manual spreadsheets, disconnected software, and hours of data entry per client. Each additional scenario compounds your workload, but not the insights you can offer.

What you need is the ability to tailor recommendations without multiplying effort. You need tools that let your recommendations flow through a broader financial plan and inform how a client’s estate plan is structured and executed.

Three Ways Intelligent Data Ingestion Saves Time Without Sacrificing Customization

Automation does not replace advisor judgment. It removes friction from places where judgment adds the most value.

Method 1

First, a secure client upload option limits eliminate unnecessary back-and-forth. You send a secure, branded link. Your client uploads their tax documents directly. The system extracts the data, allowing you to move straight to strategy instead of managing email chains.

Method 2

Second, natural language input supports early-stage planning. For prospects not ready to share full returns, you can dictate key details using Ester®. The platform captures the conversation, parses the figures, and inputs the data automatically. You don’t even have to type.

Method 3

Third, drag-and-drop PDF uploads streamline existing workflows. Simply upload a Form 1040 or W-2, and the system extracts and validates the data instantly.

In each case, automation handles data entry. You put your focus on interpretation, tradeoffs, and client-specific context. The Wealth.com platform validates the inputs, allowing you to move on quickly to apply your experience and judgment to shape next steps.

Multi-Scenario Modeling for Faster, Deeper Conversations

Modern tax planning requires flexibility. You need tools that offer speed for urgent questions as well as depth for long-term planning.

With Wealth.com’s Tax Planning, Rapid Triage Mode supports quick calculations when time matters. If a client calls with a single question, such as confirming Q4 estimated payments, you can generate answers in seconds without building a full plan.

Deep Planning Mode is its counterpart. It supports comprehensive annual reviews and life-event analysis. You can model high-impact strategies like Roth conversions and capital gains or loss harvesting, while the system calculates specific tax savings tied to each scenario.

Quick Actions and Templates further reduce friction in the planning process. You can apply standard strategies that you use over and over again, such as maximizing a 401(k) or executing a Roth conversion, with one click. Firms with established playbooks can create templates and apply them consistently across households.

This approach also enables practical what-if analysis, such as modeling the tax impact of a potential move to a different state, without rebuilding assumptions from scratch.

Tax + Estate = Compounding Value

Advisors do not think in workflows. They think in outcomes for real families.

It makes sense for tax planning and estate planning to function as a compound product. Decisions in one domain directly shape results in the other.

Wealth.com’s Tax Planning reflects how you actually deliver advice by connecting tax decisions to legal structures and handling the execution of the entire plan within a single system.

Life events such as marriage, a new child, or a change in filing status automatically surface estate planning considerations. The resulting benefit is that you gain confidence that what you plan in a meeting with a client ultimately aligns with what gets implemented.

The platform also supports complex federal and state analysis, capital gains and loss harvesting, and clear tax savings calculations without creating confusion. Each decision connects back to gifting capacity, estate structure, and legacy goals.

Delivering Client-Specific Tax Insights at Scale

Effective personalization starts with context.

Use Wealth.com’s Look Back capability to review past returns and establish a historical baseline to calculate Prior-Year Safe Harbor amounts. Recent enhancements to Ester® extend this analysis across federal and state tax documents, estate documents, and trust provisions to surface risks, conflicts, and future-state implications across a client’s plan.

These insights power Wealth.com’s redesigned Report Builder. You can deliver clearer, more actionable narratives that connect tax decisions to estate outcomes, funding gaps, and long-term objectives.

When you want to look forward and model tax scenarios for future years, you can generate Baseline Reports that combine historical data with future tax rates, as well as Projected Reports that incorporate scenario adjustments. Advanced strategies, including Roth conversions, income timing, and capital gains harvesting, are quantified with estimated tax savings tied directly to each recommendation.

Taken together, these features allow you to maintain control of the client experience while leveraging the platform’s scale and consistency to create client-specific insights.

Explore Wealth.com Tax Planning

Personalized tax planning is no longer limited to boutique firms. Wealth.com’s Tax Planning tools bring integration, automation, and intelligent modeling to every firm, making tax insights scalable across every household you serve.

To learn more about Wealth.com Tax Planning, visit wealth.com/tax.

AI Is Changing the Economics of Wealth Management. That’s Good News for Financial Advisors.

For the past several years, much of the conversation around artificial intelligence in wealth management has focused on efficiency.

Can AI summarize a meeting? Draft an email? Search a knowledge base? Prepare for a client review faster?

Those applications matter. But they may also be obscuring the much larger shift taking place.

In its 2026 Global Wealth Report, Boston Consulting Group (BCG) argues that AI is becoming a structural force in wealth management, not simply an incremental productivity tool. AI is already being applied to financial planning, portfolio management, compliance documentation and increasingly complex workflows.

That distinction matters. The first chapter of AI was about helping advisors complete individual tasks faster. The next chapter is about changing how much advice one advisor can deliver.

And if that happens at scale, the economics of wealth management begin to change with it.

The scarce resource in wealth management is advisor capacity

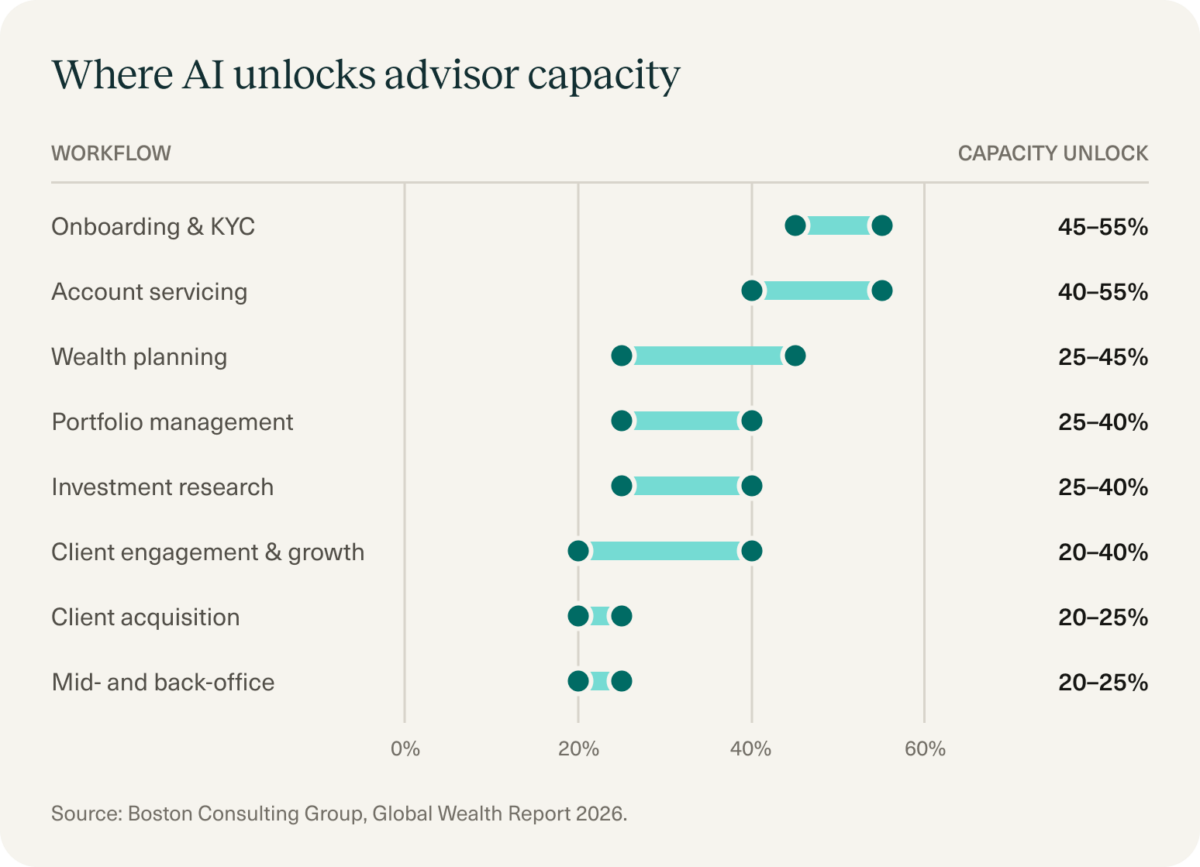
Chart illustrating the potential capacity unlocked by artificial intelligence across wealth planning, account servicing, portfolio management and client engagement.
AI has the potential to unlock significant capacity across the wealth management value chain. Source: Boston Consulting Group, 2026 Global Wealth Report.

Advice has traditionally been difficult to scale.

Every additional client creates additional work. More meetings. More preparation. More documentation. More analysis. More servicing. More follow-up.

Technology has improved many of these processes over the years, but the basic equation has remained largely intact: serving more clients generally requires more people.

AI is changing that equation.

BCG estimates that AI could unlock significant capacity across nearly every major component of the wealth management value chain.

The AI capacity opportunity
25-45%
Wealth planning

40-55%
Account servicing

25-40%
Portfolio management

20-40%
Client engagement & growth

BCG’s analysis also points to the potential for a 25% to 30% capacity unlock across planning, portfolio management and servicing, alongside 15% to 20% higher revenue per advisor.
Source: Boston Consulting Group, 2026 Global Wealth Report

Those numbers raise a more consequential question than whether advisors are using AI:

What will firms do with the capacity AI creates?

There are two very different answers.

  1. A firm can use AI primarily to lower its cost to serve.
  2. Or it can use that same capacity to deliver more advice.

The second opportunity may ultimately be the more important one.

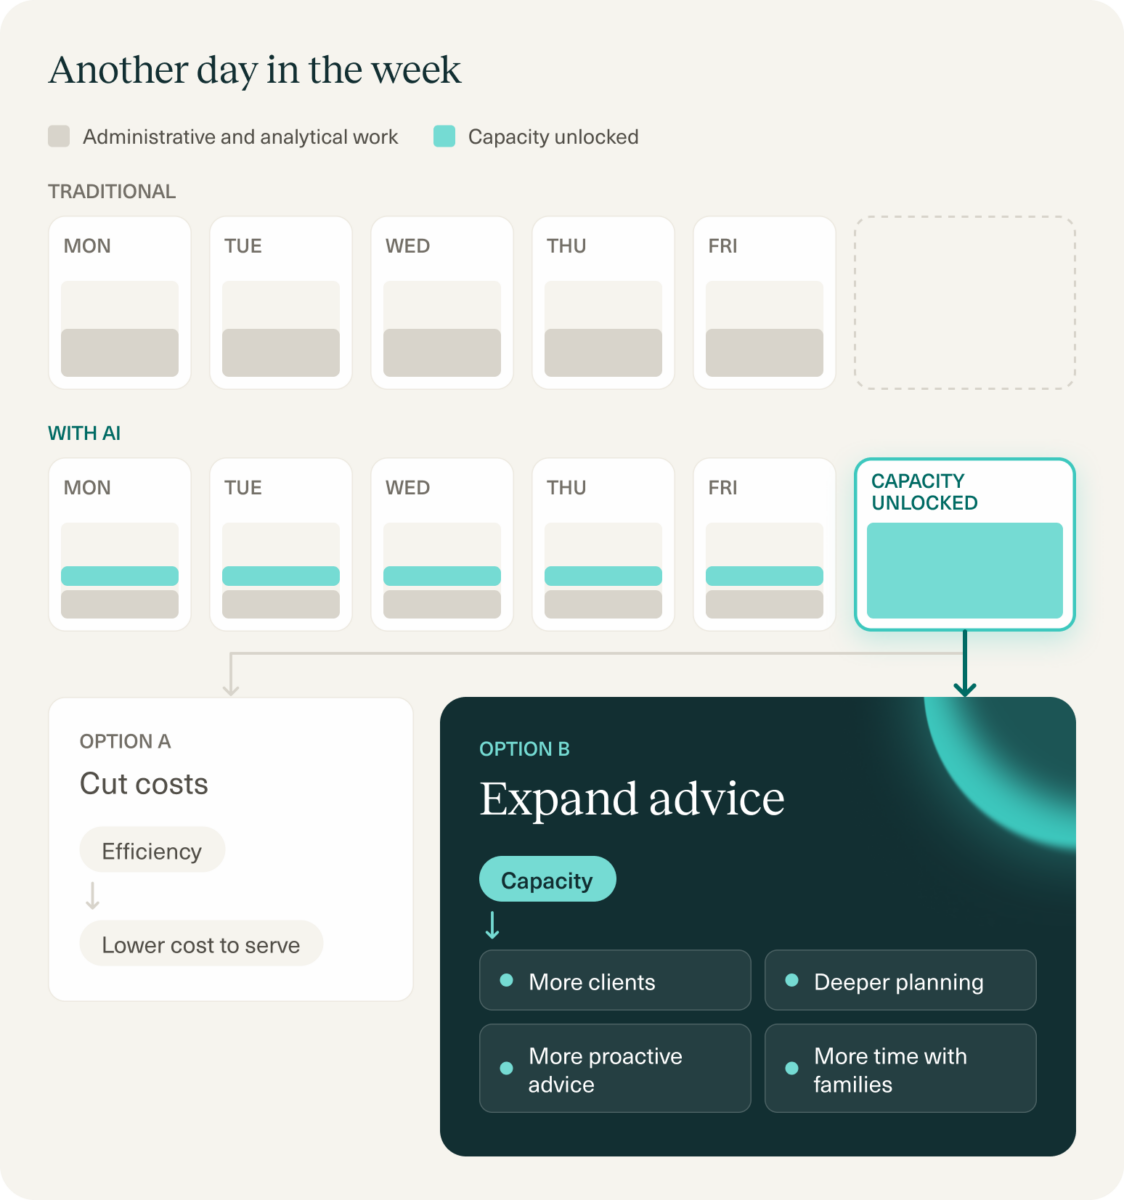
Imagine giving every advisor another day in the week

Consider what happens if technology meaningfully reduces the time advisors spend collecting information, preparing analysis, documenting meetings, servicing accounts and monitoring planning opportunities.

It is effectively the equivalent of giving advisors additional hours every week.

Illustration showing how AI-created capacity can give financial advisors more time to reinvest in client relationships and planning.
The opportunity is not simply to reduce cost. Firms can reinvest AI-created capacity in higher-value advice and stronger client relationships.

A firm could treat those hours as a cost-saving opportunity. Or it could reinvest them in the client relationship.

That could mean serving more households without sacrificing the client experience. It could mean going substantially deeper with existing clients. It could allow advisors to expand beyond traditional portfolio conversations into estate planning, tax planning, charitable strategies, business succession and multigenerational wealth planning.

It could also change the cadence of advice itself.

Historically, much of wealth management has been episodic. A client meets with an advisor periodically. Their circumstances are reviewed. Opportunities are identified. Recommendations follow.

An AI-enabled advisory model can become far more continuous.

Technology can help monitor a client’s financial life, identify relevant changes and surface potential planning opportunities between meetings. The advisor can spend less time searching for those opportunities and more time helping clients understand what they mean and what to do next.

That is a fundamentally different model of advice.

BCG reaches a similar conclusion. Rather than directing all AI-driven productivity gains toward cost reduction, the report argues that firms can deploy the capacity toward deeper relationships, higher-value services and clients who previously may not have been economical to serve.

In other words, the opportunity is not simply to make today’s wealth management model cheaper.

It is to make the model better.

AI can move the advisor up the value chain

There is an understandable fear that as AI becomes more capable, the role of the financial advisor becomes smaller.

For the best advisors, the opposite may be true.

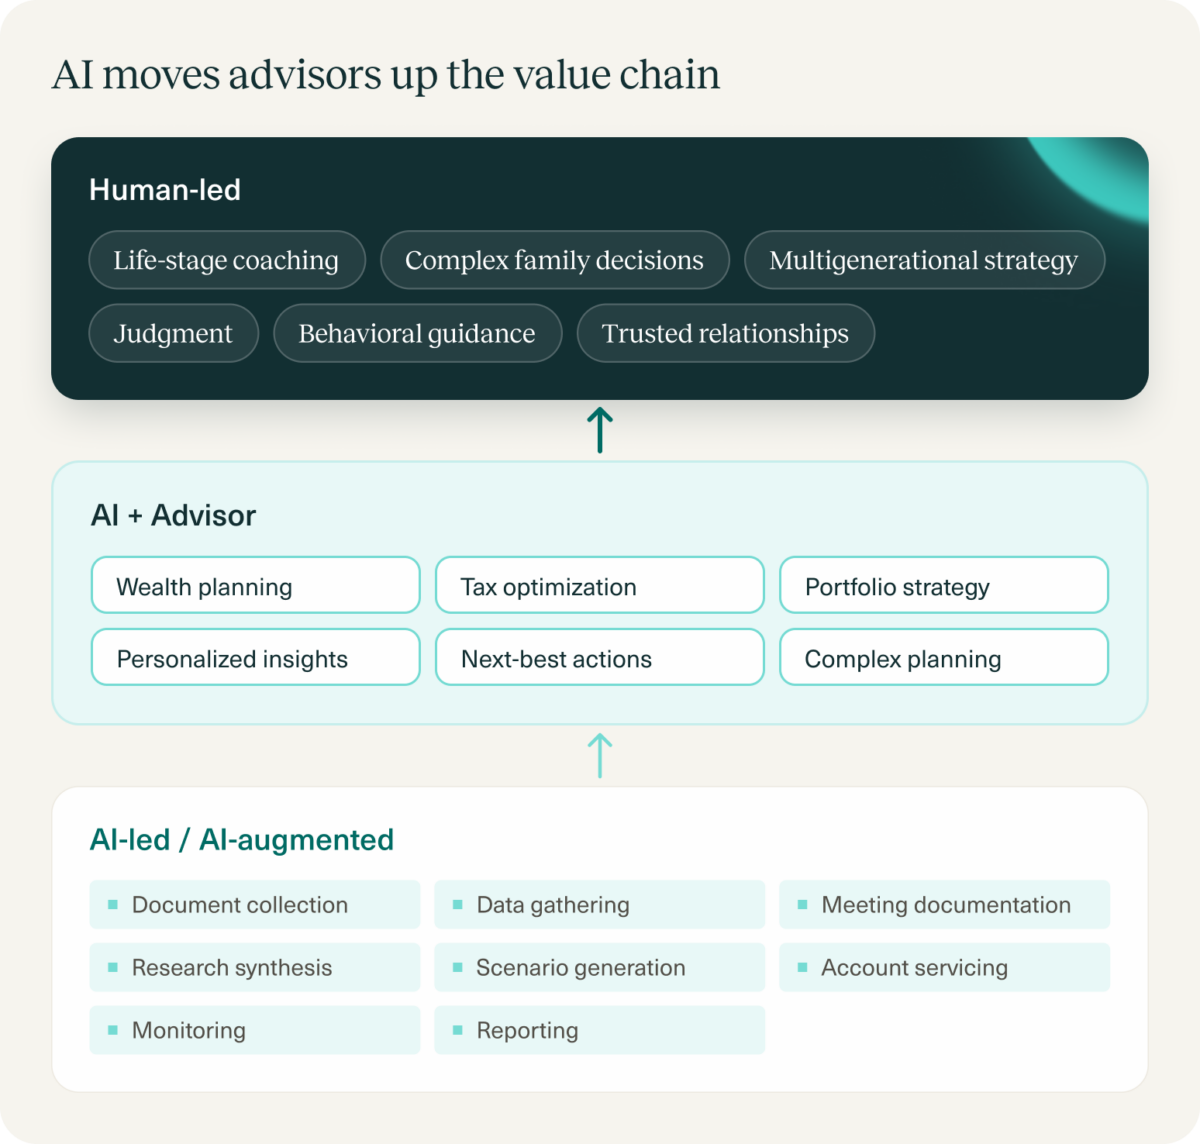
As more repeatable work becomes automated, the value of uniquely human work increases.

BCG’s analysis draws a useful distinction. Activities such as document collection and processing, scenario generation, research synthesis, regulatory reporting, transaction monitoring and routine servicing are increasingly suited to AI augmentation or automation.

Meanwhile, life-stage coaching, multigenerational strategy, complex client requests and the trusted-advisor relationship remain substantially human-led.

That suggests the role of the advisor is not disappearing.

It is becoming more concentrated around the parts of advice that matter most.

AI is most valuable when it automates the work around advice, not the relationship at the center of it.
Value ladder illustrating how artificial intelligence can shift advisor time away from repeatable tasks toward judgment, communication, coaching and complex client strategy.
As repeatable work becomes more automated, advisor value can increasingly concentrate around judgment, communication, coaching and relationships.

The advisor of the future may spend less time assembling the answer and more time helping a family understand what the answer means.

For decades, advisors have been asked to operate simultaneously as analysts, researchers, administrators, project managers, service representatives and relationship managers.

AI gives firms an opportunity to separate those responsibilities.

Technology can increasingly handle monitoring, synthesis and repeatable analysis. Advisors can devote more of their attention to judgment, communication, coaching and decision-making.

That is not a diminished role for the advisor.

It is a more valuable one.

Planning is where the economics become especially interesting

Nowhere is this shift more important than financial planning.

BCG identifies financial planning, portfolio management and compliance as both major cost pools and clear near-term opportunities for AI. Its recommendation to wealth managers is notably direct: move beyond experimentation and begin scaling AI across these workflows.

Estate and tax planning provide particularly useful examples of why the economics matter.

Both can deliver enormous value to clients, but they have historically been difficult to deliver broadly.

The work can require collecting significant amounts of information, understanding interconnected financial circumstances, analyzing documents, evaluating multiple scenarios and translating technical complexity into something a client can understand and act on.

That makes sophisticated planning expensive to deliver at scale.

As AI and modern planning technology compress the work surrounding those processes, the economics begin to change.

An advisor may be able to explore more scenarios. A firm may be able to deliver planning across a much larger portion of its client base. Planning opportunities that once required significant manual effort can increasingly be identified proactively.

The result could be a major expansion in access to sophisticated advice.

BCG points toward this possibility elsewhere in its report with what it calls the “Digital Multi-Family Office.” The model uses AI and modern infrastructure to extend capabilities traditionally associated with a multi-family office to clients with $1 million to $10 million in wealth at a fraction of the cost.

That idea has implications far beyond family offices.

AI can help push sophisticated planning further down the wealth spectrum while simultaneously allowing advisors serving high-net-worth families to go deeper.

That is not simply an efficiency gain. It is an expansion of what the industry can deliver.

But AI alone is not enough

The excitement around AI can sometimes create the impression that simply adding a large language model to an existing workflow makes a firm AI-first.

It does not.

BCG draws an important distinction between firms that layer AI onto existing processes and those that redesign workflows and processes around AI agents from the beginning. The report argues that the largest gains will accrue to organizations willing to rethink the operating model itself.

The difference can be substantial.

Adding AI to a ten-step process might make several steps faster.

Redesigning the workflow might eliminate seven of them.

That shift requires more than an AI assistant sitting beside the advisor. It requires connected data, modern infrastructure, integrated workflows and clear systems of control.

And in wealth management, it also requires recognizing that not every problem should be solved probabilistically.

That becomes particularly important in high-stakes areas such as estate and tax planning.

Generative AI can be extraordinarily powerful at interpreting information, surfacing opportunities and helping people navigate complexity. But planning also depends on accuracy, structured rules, reliable data, deterministic calculations and appropriate professional oversight.

BCG makes a similar architectural point in its recommendations for firms preparing for agentic workflows. AI agents need access to curated, real-time data, while their actions should remain governed by deterministic control layers such as transaction systems, rules engines and established workflows.

The most capable systems will not ask AI to do everything.

They will combine AI with purpose-built technology and deterministic systems so each component handles the work it is best suited to perform.

The real divide will be between AI-enabled and AI-first firms

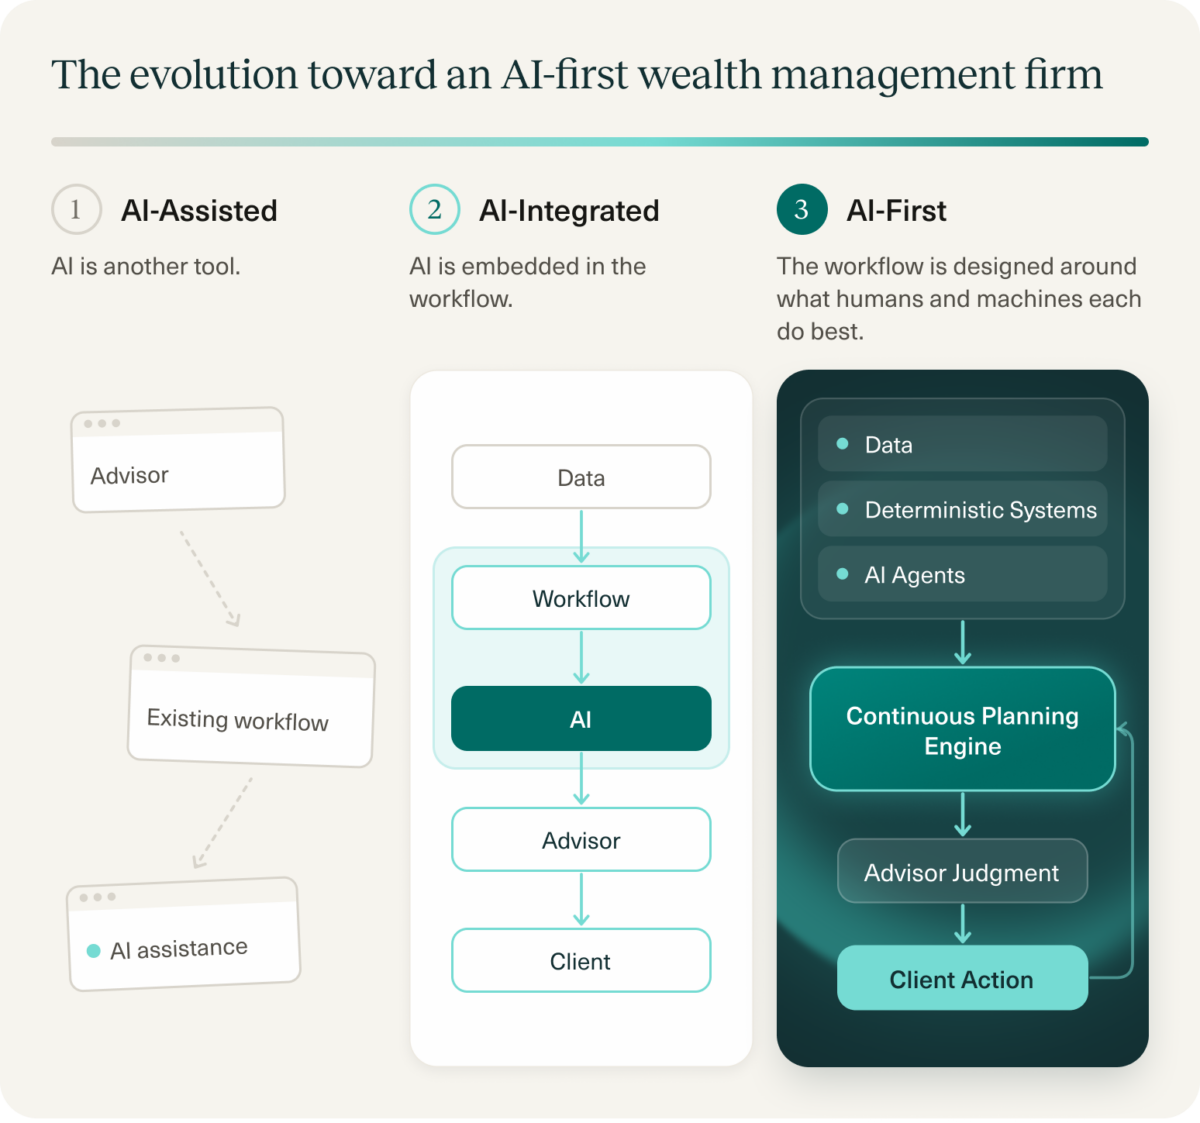
Illustration showing the progression from AI-assisted to AI-integrated to AI-first wealth management firms.
The competitive divide may ultimately be less about whether a firm adopts AI and more about how deeply it redesigns its operating model around it.

Most wealth management firms will adopt AI.

That alone will not create a lasting competitive advantage.

The larger divide will be between organizations that use AI to accelerate pieces of their current operating model and those that redesign the model itself.

An AI-assisted firm gives advisors new tools.

An AI-integrated firm embeds those tools throughout existing workflows.

An AI-first firm asks a more fundamental question:

If we were designing the advisory experience today, knowing what AI can do, how would we build it?

That question leads somewhere very different.

The advisor’s workflow changes.

The client’s experience changes.

The number of clients an advisor can effectively serve changes.

The economics of sophisticated planning change.

And eventually, client expectations change too.

Once clients experience advice that is more proactive, more personalized and more responsive, periodic reviews and reactive planning begin to feel inadequate.

That may be one of the most important competitive consequences of AI.

The firms that move first do not simply become more efficient.

They begin resetting the standard for what advice looks like.

The ceiling on advice is moving

The wealth management industry has spent years debating whether AI will replace financial advisors.

That may be the wrong question.

The more useful question is what becomes possible when advisors no longer have to spend so much of their time doing work that technology can increasingly handle.

AI can make today’s wealth management model cheaper.

But that is the least ambitious version of the opportunity.

It can also allow advisors to serve more families, deliver more sophisticated planning, identify opportunities earlier and devote more of their time to the conversations in which human judgment matters most.

BCG ultimately sees disruption, rather than displacement, as the more likely outcome. In that future, AI expands capacity across the value chain and reshapes the economics of advice without removing its human core.

That future does not diminish the advisor.

It makes the advisor more valuable.

The first era of AI in wealth management was about productivity.

The next will be about capacity.

The firms that win will be the ones that decide carefully what to do with it.

At Wealth.com, we’re building for that future: one in which technology expands the reach and depth of sophisticated planning while giving advisors more time to do what technology cannot, understand their clients, guide consequential decisions and help families Plan for Every Tomorrow.

See Wealth.com in action
Turn more advisor capacity into more valuable planning.

See how Wealth.com brings AI-powered estate and tax planning together to help advisors identify opportunities sooner, deliver sophisticated planning at scale and spend more time where their judgment matters most.

Get a Demo

The Great Wealth Transfer Begins with Women

At EstateCon 2026, four of the most influential leaders in wealth management took the stage with a unified conviction. Joanne Bradford, Strategic Advisor to Wealth.com; Kathie Chao, Managing Director at Charles Schwab; Kate Shackleton, Executive Managing Partner at Mercer Advisors; and Shannon Spotswood, CEO of RFG Advisory, made it clear: the Great Wealth Transfer will not just include women, it will be shaped and directed by them.

This article advances the insights shared on stage and translates them into strategic implications for your firm’s growth plans.

An estimated $124 trillion is expected to change hands over the next two decades. A significant share of that capital will be controlled by women through inheritance, divorce settlements, liquidity events, and rising earnings power.

For advisors, this is a structural shift from how the industry has traditionally operated, and it necessitates operational change and a shift in approach to client relationships.

If your firm intends to lead during the Great Wealth Transfer, the following seven insights outline how firms can position themselves to serve women in wealth with clarity and purpose.

1. The Center of Gravity Is Shifting

The Great Wealth Transfer is frequently described as an intergenerational event, but its immediate impact is not necessarily limited to parents and their children.

Women are projected to control over $30 trillion in assets by the end of this decade. At the same time, younger cohorts of women are investing earlier and engaging more actively in financial decision-making than prior generations.

This shift requires more than revised marketing language. It requires acknowledging that women in wealth are not peripheral beneficiaries of capital transitions.

They are the primary decision-makers, business owners, executives, and wealth creators. In fact, in more than two-thirds of households in the United States today, women are the ones making the primary decisions when it comes to investing.

If an advisory firm treats women as a secondary initiative, it will struggle to compete with firms that recognize women clients in the primary position that they deserve.

2. The Retention Gap Is a Risk to Firm Growth

Industry data shows that as many as 80% of widows leave their financial advisor within a year of their spouse’s death. Divorce produces similar patterns of attrition.

When so much money is in motion, retention failure becomes a material economic risk to the continued growth of an advisory firm.

Many women report feeling overlooked in meetings with their advisor, excluded from technical discussions, or addressed through their spouse rather than as an equal participant. Jargon-heavy communication reinforces distance rather than trust.

For advisors, the implication is easy to understand. Engagement must be intentional, inclusive, and designed for both spouses from the outset. Modern estate planning offers one of the most effective entry points to get that alignment correct.

3. Education Builds Agency

Research consistently shows that a majority of women—eighty-five percent—wish they had begun investing earlier. That regret reflects a lack of access to clear, practical financial education delivered at the right moment, not a lack of ability.

Women often approach financial decisions through scenario modeling. Questions such as “When can I retire?” or “How would a move affect our plan?” reflect a desire to understand trade-offs and future outcomes. Purpose-driven financial advice can meet that need by connecting technical planning to clearly defined life goals and long-term outcomes.

Modern estate planning supports this framework by visualizing asset flow, beneficiary structures, and long-term impact in ways that are accessible without oversimplifying complexity.

4. Estate Planning Is a Strategic Engagement Tool

Many advisors may have begun their career focused on investment management, but today’s focus on more comprehensive financial guidance means that estate planning can often create the most inclusive conversation.

Estate planning brings both spouses into the discussion, introduces next-generation heirs, and surfaces values that extend far beyond portfolio allocation or retirement planning.

When estate planning is paper-heavy, attorney-centric, and disconnected from the broader advisory workflow, it reinforces friction. When it is delivered through a secure, digital, advisor-first platform, it easily becomes a collaborative process that strengthens the client-advisor relationship.

The Great Wealth Transfer will reward firms that treat modern estate planning as a strategic growth lever rather than a compliance exercise. Advisors who integrate estate, tax, and financial planning into a comprehensive client experience will be positioned to retain more assets across transitions.

5. Women Are a Business Segment

Serving women in wealth requires deliberate strategy. You cannot reduce your plan to hosting a single event or assigning a female advisor to cover relationships.

Firms that succeed in this space treat women as a defined buying segment with particular priorities, specific communication preferences, and differentiated life stages.

Here’s what you can do to be more effective. Train your advisors to conduct needs-based conversations, design events that address financial stress felt more intimately by women, and align your marketing outreach to resonate with the real-world concerns expressed by women.

Firms should also systematically gather feedback from the women they already serve and incorporate those insights into their practice design and communication strategy.

It has been studied and known for decades that women refer business to their advisors at higher rates than men. In the context of the Great Wealth Transfer, that referral dynamic has the potential to further compound growth as your firm works with more women.

6. Digital Expectations Have Evolved

The trend of clients increasingly looking outside their advisor for answers is only growing with the evolution of AI.

Today’s clients can model retirement scenarios, research estate structures, and consult Google or AI to explore nuanced and sophisticated financial outcomes, all without the help of their advisor.

These behaviors aren’t replacing their advisor, but they are reshaping expectations about access, responsiveness, and the digital client experience.

When it comes to women, who are more likely to balance professional and family responsibilities, engaging with financial content outside traditional hours can be the norm.

An advisory model limited to quarterly reviews and PDF or paper documents does not align with that reality. Modern estate planning has to be accessible, secure, and designed for ongoing collaboration.

Is your technology doing its part to reduce friction with document review, beneficiary updates, and collaboration? Integrating better estate technology into your advisor workflow before clients, especially women, start to push back on a lack of flexibility can help you get ahead of the conversation.

7. Operational Excellence Determines Outcomes

It’s time to clear up operational fragmentation within your firm. Advisors who spend a majority of their day on manual processes, working within disconnected systems, or spending time on non-revenue-generating tasks will struggle to scale their advice and relationships.

Women in wealth increasingly expect integrated planning across investments, taxes, and estate strategy. Delivering purpose-driven financial advice at scale requires a well-run firm supported by secure, integrated technology.

Firms that professionalize their operations, invest in training, and adopt comprehensive platforms will be able to focus on their core superpower: building trust.

Advancing the Conversation with Wealth.com

The EstateCon panel made clear that the Great Wealth Transfer begins with women. The next step for advisors is to translate that insight into structural change. Engaging women intentionally, modernizing estate planning delivery, and committing to operational excellence are strategic imperatives.

Our platform was built to support this moment. By modernizing how estate plans are created, visualized, and maintained, you can deliver the clarity and confidence that your clients expect, no matter their gender.

The Q4 Planning Playbook: Tax and Estate Conversations to Have With Every Client

A strong year-end plan starts before year-end feels urgent.

October still gives advisors time to find the issues. November creates room to compare options and make decisions. By December, the work needs to move from recommendation to execution.

Too often, all three phases are compressed into one year-end client meeting agenda. The advisor reviews performance, asks about charitable giving, checks required minimum distributions, raises tax-loss harvesting, mentions outdated estate documents, and sends a long follow-up list. The conversation may be comprehensive, but the window to act is already closing.

Effective Q4 financial planning follows a sequence:

October
Reveals
November
Decides
December
Executes

That sequence turns the annual review from a retrospective meeting into a coordinated tax and estate planning process.

What should a year-end planning checklist for advisors include?

A year-end planning checklist for advisors should cover projected income and tax liability, withholding and estimated payments, realized and unrealized gains and losses, retirement distributions, charitable giving, family gifts, estate documents, beneficiary designations, asset titling, trust funding, and material life changes.

The checklist becomes more useful when it is spread across three stages instead of treated as a single meeting:

October
Reveal

Primary objective

Build the baseline and identify gaps.

Client outcome

A prioritized planning inventory.

November
Decide

Primary objective

Model tradeoffs and approve recommendations.

Client outcome

A documented action plan.

December
Execute

Primary objective

Complete, confirm, and record each action.

Client outcome

A closed-loop implementation record.

This structure gives the advisor, client, CPA, attorney, and other specialists enough time to work from the same information without forcing every decision into the final weeks of the year.

Before the first Q4 meeting: Build the client’s current planning record

The quality of a Q4 meeting depends on what is known before it begins. If the advisor spends October gathering documents one at a time, November becomes the discovery phase and December becomes a scramble.

Before the first meeting, collect or confirm:

  • The most recently filed federal and state tax returns
  • Current-year income, withholding, and estimated tax payments
  • Expected bonuses, business income, equity compensation, or liquidity events
  • Realized gains and losses, plus significant unrealized positions
  • Retirement contributions, distributions, and required minimum distribution status
  • Charitable giving and family gifting completed or contemplated during the year
  • Current estate documents and the date of the last review
  • Beneficiary designations and ownership of major assets
  • Trusts, entities, insurance policies, and business interests
  • Family, employment, residency, health, or ownership changes
  • Open recommendations from the prior annual review

For clients who requested an extension, October may also be the first time the completed prior-year return is available for planning. For 2026, the federal filing deadline for most individual taxpayers with an extension is October 15. An extension to file did not extend the original deadline to pay. See IRS filing guidance.

The filed return should not be treated as historical paperwork. It is the starting data set for the next recommendation.

October: Reveal the full planning picture

October is the diagnostic month. The advisor’s job is to establish what changed, where the client is likely to finish the year, and which decisions have a real deadline.

Start with the tax baseline

Compare the most recent return with current-year expectations. Look for changes in:

  • Salary, bonus, self-employment income, or business distributions
  • Interest, dividends, capital gains, and investment income
  • Stock option exercises, restricted stock vesting, or concentrated equity
  • Retirement contributions and distributions
  • Itemized deductions and charitable activity
  • State residency or multistate income
  • Withholding and estimated tax payments
  • Carryforwards, credits, or other items identified by the client’s tax professional

The goal is not to finalize the return in October. It is to create a credible current-year projection and identify the variables that could still change.

Run the estate alignment scan

Tax planning should not begin and end with the income tax return. Ask what changed in the client’s life and ownership structure during the year:

  • Was there a marriage, divorce, birth, death, or change in family relationships?
  • Did the client move to another state or buy property there?
  • Was a business formed, sold, recapitalized, or materially revalued?
  • Did the client inherit assets or begin supporting another family member?
  • Are the named fiduciaries and beneficiaries still appropriate?
  • Were previously created trusts actually funded?
  • Do beneficiary designations and account titles match the estate plan?
  • Has the client’s expected estate tax exposure materially changed?

An annual estate review does not require the advisor to reopen every document each year. It does require enough visibility to recognize when a legal review is warranted.

Triage by deadline, impact, and dependency

Not every planning opportunity belongs on the Q4 action list. Rank each item using three questions:

1
Deadline

Must the action occur during the current calendar year?

2
Impact

Is the potential benefit or avoided risk material to the client?

3
Dependency

Does execution require a CPA, attorney, custodian, trustee, valuation professional, or family decision?

The output from October should be a short planning inventory divided into three categories: act this year, prepare for next year, and monitor.

That clarity protects the client from an overwhelming checklist and protects the advisory team from treating every idea as equally urgent.

November: Decide which strategies belong in the plan

November is the decision month. The baseline is established, the planning gaps are visible, and there is still time to evaluate tradeoffs before operational deadlines take over.

Model the tax alternatives

Depending on the client, the November analysis may include:

  • Roth conversion scenarios
  • Capital gain or loss harvesting
  • Charitable gifts of cash or appreciated assets
  • Qualified charitable distributions for eligible IRA owners
  • Income, deduction, or business expense timing
  • Withholding or estimated tax adjustments
  • Retirement plan contribution opportunities
  • Equity compensation exercises or sales
  • State residency and multistate tax considerations
  • Business owner compensation, distributions, or liquidity events

The recommendation should quantify more than the current-year tax result. A decision that lowers this year’s tax bill may increase future exposure, reduce liquidity, alter the investment plan, or create an unintended estate consequence.

Connect every tax recommendation to the estate plan

Tax and estate decisions are connected by ownership, cash flow, and time. The advisor should make those connections explicit.

Tax decisionPotential estate or planning consequenceQuestion to resolve
Roth conversionChanges current income, future retirement balances, and the assets heirs may inheritDoes the long-term family benefit justify the current tax cost?
Gift of appreciated assetsReduces the donor’s ownership and may shift future appreciationIs the transfer consistent with the client’s liquidity and inheritance goals?
Charitable contributionChanges cash flow, portfolio composition, and the assets remaining for familyIs the giving strategy coordinated with the broader legacy plan?
Capital gain or loss harvestingChanges taxes, basis, and portfolio exposuresDoes the tax action support the investment plan rather than distort it?
Business income or equity decisionCan affect tax liability, valuation, liquidity, and ownership concentrationDoes the personal tax strategy align with business succession and estate planning?

This is where integrated year-end planning becomes more valuable than a collection of separate calculations. The advisor is not simply asking, “How much tax could this save?” The advisor is asking, “What else changes if the client does it?”

Finalize the estate actions

November is also the time to determine whether any estate-related action should be completed before year-end:

  • Annual gifts to family members or trusts
  • Trust contributions and related administrative requirements
  • Charitable gifts that support the client’s tax and legacy goals
  • Beneficiary designation changes
  • Account or property retitling
  • Funding of an existing revocable or irrevocable trust
  • Updates prompted by a family, fiduciary, residency, or ownership change
  • Insurance ownership or beneficiary reviews
  • Business succession, buy-sell, or valuation work that requires specialist involvement

For 2026, the federal gift tax annual exclusion is $19,000 per recipient, with separate exclusions generally available to each spouse. Gifts of future interests and gift splitting can involve additional rules and filing requirements, so the client’s attorney and tax professional should guide the structure and reporting. See the IRS gift tax FAQs.

The fact that an annual exclusion is available does not mean every client should use it. Gifting decisions should begin with the client’s financial security, intent, family dynamics, and long-term estate strategy.

End November with a decision record

Every approved recommendation should identify:

  • The action to be completed
  • Why it supports the client’s goals
  • The amount or key assumption involved
  • The person responsible
  • The required specialist or custodian
  • The operational deadline
  • The evidence that will confirm completion

The advisor should also record recommendations the client declined or deferred. That preserves context and gives next year’s annual client review framework a much stronger starting point.

December: Execute, confirm, and close the loop

December should not be the month when the planning team first discovers a complex gift, outdated trust, missing valuation, or unresolved family decision.

It should be the month when approved actions move through a controlled execution process.

Use an execution calendar, not one final deadline

Many strategies may have a December 31 tax deadline, but custodians, charities, payroll teams, attorneys, trustees, and financial institutions often require earlier processing. Create internal deadlines that leave room for rejected paperwork, missing signatures, market closures, asset valuation, and client hesitation.

A practical cadence is:

Early December

Reconfirm assumptions, secure final client approval, and initiate transfers or paperwork.

Mid-December

Verify processing, signatures, valuations, notices, and specialist deliverables.

Final business days

Resolve exceptions and confirm completion. Avoid introducing strategies that cannot be implemented responsibly.

Confirm the year-end tax actions

Depending on the client’s plan, the advisor and tax professional may need to confirm:

  • Required minimum distributions have been completed
  • Qualified charitable distributions have reached the intended charity
  • Charitable contributions intended for the current tax year have been made and can be substantiated
  • Approved Roth conversions have been processed
  • Planned gain or loss transactions have been completed
  • Withholding and estimated payment decisions have been implemented
  • Retirement plan contributions subject to a calendar-year deadline have been addressed
  • Business, equity compensation, or liquidity actions have been completed as intended

Most retirement account owners subject to required minimum distributions must receive them by December 31, although special timing rules can apply to a first RMD. See the IRS RMD guidance. Charitable contributions generally must be paid in cash or property before the close of the individual’s tax year to be deductible for that year, and substantiation rules apply. See IRS Publication 526.

Confirm the estate actions

Estate-related completion may include:

  • Signed estate planning documents
  • Confirmed beneficiary changes
  • Completed account or property retitling
  • Verified trust funding
  • Completed family or trust gifts
  • Required trust notices and administrative records
  • Updated insurance ownership or beneficiaries
  • Stored copies of executed documents and valuation materials
  • A clear list of items that remain with the attorney, CPA, trustee, or client

Execution is not complete because a form was sent. It is complete when the advisory team can verify the intended result.

A repeatable annual client review framework

The same seven-part framework can anchor fourth quarter advisor planning across the client base:

Update: What changed in the client’s life, family, income, assets, entities, and residency?

Baseline: Where is the client likely to finish the year for tax and estate purposes?

Identify: Which opportunities, gaps, and risks deserve attention?

Model: How do the available strategies change taxes, liquidity, ownership, and long-term outcomes?

Decide: Which recommendations does the client approve, decline, or defer?

Execute: Who owns each action, and how will completion be verified?

Carry forward: What should be monitored or prepared in the next calendar year?

The framework stays consistent, but the agenda should change with the client.

Retirees

Prioritize RMDs, qualified charitable distributions, withholding, Medicare-related income considerations, Roth conversions, beneficiary designations, and trust alignment.

Business owners

Prioritize projected business income, estimated payments, retirement contributions, valuation changes, liquidity, succession, buy-sell agreements, and the ownership of business interests.

Executives and equity-compensated clients

Prioritize vesting, option exercises, withholding, concentrated stock, gain recognition, charitable transfers, liquidity, and the estate impact of growing equity value.

Families accumulating wealth

Prioritize changing income, workplace benefits, education funding, insurance, guardians, beneficiary designations, powers of attorney, and foundational estate documents.

High-net-worth and multigenerational families

Prioritize trust funding, gifting, charitable planning, entity ownership, insurance, estate tax exposure, fiduciary decisions, and coordination across generations.

“Every client” should not mean “the same checklist for every client.” It should mean that every client receives a consistent planning process built around the issues that actually apply to them.

Why unified tax and estate workflows matter most in Q4

Fragmented planning creates repeated handoffs. A tax return is uploaded into one system, projections are built in another, estate documents sit in a separate vault, and execution is tracked through email or spreadsheets. Each handoff creates another opportunity to lose assumptions, duplicate work, or miss the connection between a tax recommendation and an estate outcome.

A unified workflow allows the advisor to move through one continuous process:

Review tax returns, estate documents, ownership, and household information.
Establish a current tax and estate baseline.
Identify and model planning opportunities.
See how a recommendation affects taxes, liquidity, estate distributions, and family outcomes.
Present a clear recommendation to the client.
Coordinate the attorney, CPA, custodian, or other specialist.
Track execution and preserve the decision record for the next review.

Wealth.com brings tax and estate planning into one advisor-led platform. Advisors can securely ingest tax documents such as Form 1040 and W-2, establish a historical baseline, build forward-looking projections, model strategies, and connect those decisions to estate documents, legal structures, and client reporting. Explore Wealth.com Tax Planning.

That continuity is particularly valuable in Q4. Advisors can move from review to recommendation to execution without rebuilding the client’s story every time the work crosses from tax planning into estate planning.

The goal is not a longer checklist

The best Q4 tax and estate strategies are not the ones that create the most activity. They are the ones that help the client make the right decisions while there is still time to complete them.

October reveals the planning picture. November turns analysis into decisions. December turns those decisions into completed work.

That is what moves Q4 financial planning beyond an annual review. It becomes an operating system for proactive advice.


Ready to connect tax planning, estate strategy, and execution in one continuous workflow?


See how Wealth.com helps advisors plan with greater clarity and confidence.

Frequently asked questions about Q4 financial planning

When should advisors begin year-end planning?

Advisors should begin collecting data and identifying planning issues by October, or earlier for clients with complex tax, estate, business, or charitable needs. Waiting until December can leave too little time for modeling, specialist review, signatures, transfers, and custodial processing.

What should be included in a year-end client meeting agenda?

The agenda should address material life changes, projected income and tax liability, withholding and estimated payments, investment gains and losses, retirement distributions, charitable giving, family gifts, beneficiary designations, estate documents, trust funding, and open implementation items.

Which planning actions may need to be completed by December 31?

Depending on the client, year-end actions may include required minimum distributions, charitable contributions, Roth conversions, capital gain or loss transactions, certain retirement plan contributions, family or trust gifts, and other tax-sensitive transfers. Operational deadlines may occur before December 31, and clients should confirm requirements with their tax, legal, and financial professionals.

How should tax and estate planning be coordinated?

Each tax recommendation should be evaluated for its effect on liquidity, asset ownership, estate value, beneficiaries, and long-term family outcomes. Each estate action should also be evaluated for its current and future tax consequences. Advisors can help coordinate the client’s attorney, CPA, and other specialists around one set of facts and goals.

Does every client need the same Q4 planning checklist?

No. Every client should receive the same disciplined review process, but the specific agenda should reflect the client’s age, income, assets, family, business interests, estate complexity, and planning goals.


This material is for educational purposes only and is not intended to provide legal, tax, accounting, or investment advice. Clients should consult qualified professionals regarding their individual circumstances.

1 2 3 … 16