How Advisors Use Tax Software to Deliver Personalized Planning at Scale

For your clients, personalized tax planning is an expectation.

And as a financial advisor, you know that tax strategies should reflect each client’s income sources, residency, business ownership, and long-term goals.

But delivering truly customized guidance across hundreds of households creates operational inefficiency as clients ask for more precision and accountability.

This gap creates a missed opportunity, especially if you consider how closely linked taxes and estate planning should be.

Tax planning and estate planning are inseparable components of a complete financial plan, but the industry has historically treated them as disconnected disciplines. The result is advice that optimizes for moments-in-time instead of compounding value across years.

The Wealth.com Tax Planning tools change that dynamic.

By integrating tax and estate planning with intelligent automation, advisors can move beyond calculating a tax bill and toward architecting a client’s future.

Here’s how your firm can deliver personalized tax planning at scale with these tools.

The Personalization Problem in Tax Planning

No two tax situations are ever alike. Situations between clients differ across income sources, state residency, equity compensation, business ownership, charitable preferences, and family structure. Even within the same household, small changes in the life of one person can materially alter planning outcomes for an entire family.

Traditional tax planning workflows are not built for this level of variation.

Advisors rely on manual spreadsheets, disconnected software, and hours of data entry per client. Each additional scenario compounds your workload, but not the insights you can offer.

What you need is the ability to tailor recommendations without multiplying effort. You need tools that let your recommendations flow through a broader financial plan and inform how a client’s estate plan is structured and executed.

Three Ways Intelligent Data Ingestion Saves Time Without Sacrificing Customization

Automation does not replace advisor judgment. It removes friction from places where judgment adds the most value.

Method 1

First, a secure client upload option limits eliminate unnecessary back-and-forth. You send a secure, branded link. Your client uploads their tax documents directly. The system extracts the data, allowing you to move straight to strategy instead of managing email chains.

Method 2

Second, natural language input supports early-stage planning. For prospects not ready to share full returns, you can dictate key details using Ester®. The platform captures the conversation, parses the figures, and inputs the data automatically. You don’t even have to type.

Method 3

Third, drag-and-drop PDF uploads streamline existing workflows. Simply upload a Form 1040 or W-2, and the system extracts and validates the data instantly.

In each case, automation handles data entry. You put your focus on interpretation, tradeoffs, and client-specific context. The Wealth.com platform validates the inputs, allowing you to move on quickly to apply your experience and judgment to shape next steps.

Multi-Scenario Modeling for Faster, Deeper Conversations

Modern tax planning requires flexibility. You need tools that offer speed for urgent questions as well as depth for long-term planning.

With Wealth.com’s Tax Planning, Rapid Triage Mode supports quick calculations when time matters. If a client calls with a single question, such as confirming Q4 estimated payments, you can generate answers in seconds without building a full plan.

Deep Planning Mode is its counterpart. It supports comprehensive annual reviews and life-event analysis. You can model high-impact strategies like Roth conversions and capital gains or loss harvesting, while the system calculates specific tax savings tied to each scenario.

Quick Actions and Templates further reduce friction in the planning process. You can apply standard strategies that you use over and over again, such as maximizing a 401(k) or executing a Roth conversion, with one click. Firms with established playbooks can create templates and apply them consistently across households.

This approach also enables practical what-if analysis, such as modeling the tax impact of a potential move to a different state, without rebuilding assumptions from scratch.

Tax + Estate = Compounding Value

Advisors do not think in workflows. They think in outcomes for real families.

It makes sense for tax planning and estate planning to function as a compound product. Decisions in one domain directly shape results in the other.

Wealth.com’s Tax Planning reflects how you actually deliver advice by connecting tax decisions to legal structures and handling the execution of the entire plan within a single system.

Life events such as marriage, a new child, or a change in filing status automatically surface estate planning considerations. The resulting benefit is that you gain confidence that what you plan in a meeting with a client ultimately aligns with what gets implemented.

The platform also supports complex federal and state analysis, capital gains and loss harvesting, and clear tax savings calculations without creating confusion. Each decision connects back to gifting capacity, estate structure, and legacy goals.

Delivering Client-Specific Tax Insights at Scale

Effective personalization starts with context.

Use Wealth.com’s Look Back capability to review past returns and establish a historical baseline to calculate Prior-Year Safe Harbor amounts. Recent enhancements to Ester® extend this analysis across federal and state tax documents, estate documents, and trust provisions to surface risks, conflicts, and future-state implications across a client’s plan.

These insights power Wealth.com’s redesigned Report Builder. You can deliver clearer, more actionable narratives that connect tax decisions to estate outcomes, funding gaps, and long-term objectives.

When you want to look forward and model tax scenarios for future years, you can generate Baseline Reports that combine historical data with future tax rates, as well as Projected Reports that incorporate scenario adjustments. Advanced strategies, including Roth conversions, income timing, and capital gains harvesting, are quantified with estimated tax savings tied directly to each recommendation.

Taken together, these features allow you to maintain control of the client experience while leveraging the platform’s scale and consistency to create client-specific insights.

Explore Wealth.com Tax Planning

Personalized tax planning is no longer limited to boutique firms. Wealth.com’s Tax Planning tools bring integration, automation, and intelligent modeling to every firm, making tax insights scalable across every household you serve.

To learn more about Wealth.com Tax Planning, visit wealth.com/tax.

Why Single-Tenant Architecture Matters for Modern Wealth Management Firms

A bank and an independent advisory firm may use estate and tax planning technology to help clients answer many of the same questions. How will their wealth transfer? How do their estate documents fit together? What planning opportunities deserve attention?

But the environments in which that technology must operate can look very different.

For an advisory firm, the priority may be bringing sophisticated planning into everyday client conversations through a secure, dependable platform. A large financial institution needs those same capabilities, but may also have specific requirements around infrastructure isolation, vendor risk, integrations, resource allocation and change management.

That is where single-tenant architecture becomes relevant.

The vast majority of Wealth.com customers use our multi-tenant environment. For most firms, that is the appropriate deployment model. For institutions with additional infrastructure and operating requirements, Wealth.com also offers a dedicated, single-tenant environment.

What does single-tenant architecture mean?

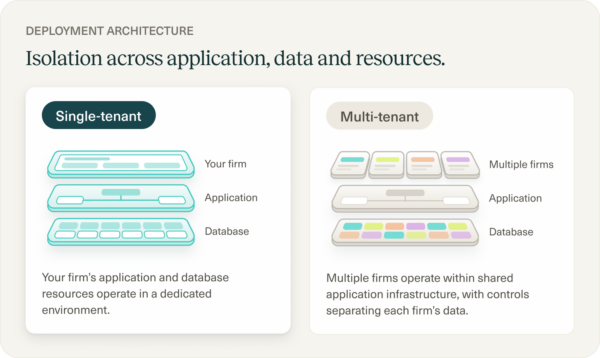
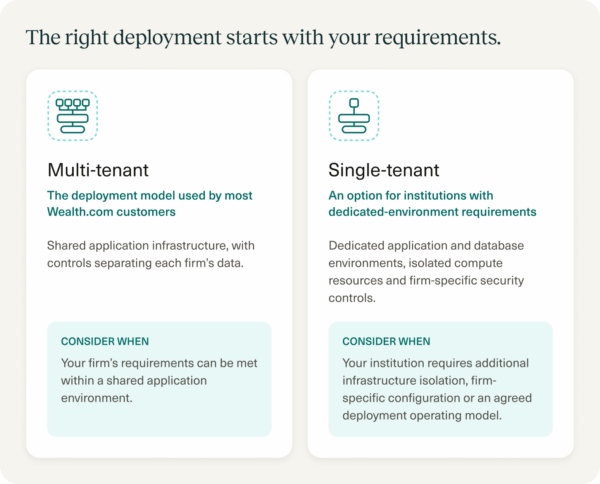
Diagram comparing single-tenant and multi-tenant deployment architecture.

Tenancy describes how a software platform’s application environment and supporting resources are organized across customers.

In a multi-tenant environment, multiple firms operate within shared application infrastructure, with controls separating each firm’s data.

In a single-tenant environment, one firm’s application and database resources operate within a dedicated environment. Wealth.com’s single-tenant deployment also includes isolated compute resources and firm-specific security controls across networking, encryption, identity and monitoring.

The important distinction is that sharing infrastructure is not the same as sharing access to information. A multi-tenant deployment uses controls to maintain separation between firms within the shared environment. Single tenancy changes how that separation is implemented and how the environment can be configured and operated for an individual institution.

Why institutional requirements can be different

A family’s estate and tax information deserves protection whether its advisor works at an independent RIA or a national bank.

What changes is not the importance of the information. It is the organizational environment surrounding it.

For a large financial institution, evaluating a planning platform may involve questions that extend well beyond the advisor experience. Which application and database resources are dedicated to the institution? How are access and monitoring scoped? Can integrations accommodate the institution’s systems? How will changes be coordinated?

These are questions about how technology fits within an operating model.

One useful way to think about single tenancy is to ask where the application, data and resource boundaries sit. Wealth.com’s dedicated deployment establishes those boundaries around an individual firm’s application and database environment, with firm-specific controls supporting assessment and oversight.

That can be valuable when an institution needs a more specifically scoped environment rather than additional functionality in the software itself.

At institutional scale, how a platform is deployed can matter alongside what it enables advisors to do.

Three reasons institutions may choose a dedicated environment

The value of single tenancy becomes clearer when translated from architecture into the work technology and security teams need to perform.

1. A defined environment for security oversight and vendor risk

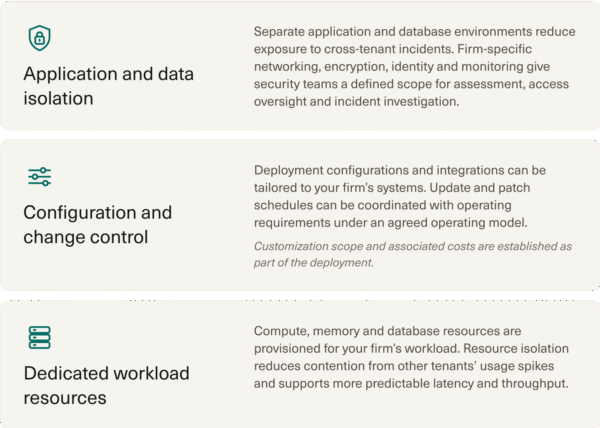
Separate application and database environments reduce exposure to cross-tenant incidents. Firm-specific networking, encryption, identity and monitoring also give security teams a defined scope for assessment, access oversight and incident investigation.

For an institution evaluating a planning platform, that scope matters. It helps focus the review on the environment supporting its own deployment: the relevant application, database, resources and controls.

Wealth.com’s single-tenant offering is designed to reduce cross-tenant dependencies and provide a clearly scoped environment for vendor-risk assessment.

The benefit is not a promise that risk disappears. It is a more defined deployment boundary within which the institution and its technology provider can assess and manage it.

2. Configuration and change management aligned with the institution

The value of enterprise software depends partly on how well it fits the systems and processes already in place.

Consider an institution introducing a planning platform alongside its existing technology. The evaluation may include not only whether an integration is available, but how it will be configured and how subsequent changes will be coordinated with operations.

Wealth.com’s single-tenant deployment allows configurations and integrations to be tailored to a firm’s systems. Update and patch schedules can also be coordinated with operating requirements under an agreed operating model. Customization scope and associated costs are established as part of the deployment.

This is a practical distinction. The value is not unlimited customization or unrestricted control over updates. It is the ability to establish an agreed approach to configuration and change that reflects the institution’s requirements.

For a bank or large wealth management organization, that alignment can be an important part of making a platform workable across the enterprise.

3. Resources provisioned for the firm’s workload

Single tenancy also changes how resources are allocated.

In Wealth.com’s dedicated environment, compute, memory and database resources are provisioned for the firm’s workload. Resource isolation reduces contention from other tenants’ usage spikes and supports more predictable latency and throughput.

For an institution assessing a broad deployment, this provides a concrete topic for capacity planning: what resources its workload requires and how those resources will be provisioned.

Estate and tax planning deserve a place in the infrastructure conversation

Estate and tax planning involve more than a set of calculations or reports. They bring sensitive information about a family’s finances, documents and relationships into the planning process.

Wealth.com’s single-tenant deployment is designed to establish a defined environment for that estate, tax and family information.

For an institution considering how to deliver planning across its organization, the evaluation should therefore address both sides of the decision.

The wealth management team needs to understand how the platform will support advisors and clients. The technology and security teams need to understand how the deployment will fit the institution’s requirements.

Those conversations should inform one another. A strong advisor experience does not remove the need for infrastructure diligence, and a well-defined deployment does not replace the need for useful planning capabilities.

Institutions should be able to evaluate both without treating one as an afterthought.

Does every wealth management firm need single tenancy? No.

Comparison of deployment models for wealth management firms.

Single tenancy is not a required next step for every growing advisory firm.

The vast majority of Wealth.com customers operate in our multi-tenant environment. Choosing that deployment does not mean a firm places less importance on security or that its clients’ information deserves less protection.

It means a dedicated application and database environment may not be necessary to meet that firm’s requirements.

There is also an investment associated with operating a separate deployment. Wealth.com’s single-tenant offering supports dedicated application and database environments, firm-specific networking and encryption, dedicated identity and monitoring, environment provisioning and ongoing operational support.

Those resources and operating arrangements should serve a defined need.

For most advisory firms, the decision will not turn on whether dedicated infrastructure sounds more sophisticated. It should turn on whether their requirements call for that infrastructure and the associated operating model.

The same principle applies to large organizations. Size alone should not decide the architecture. The institution’s requirements should.

What institutions should ask planning technology providers

A useful evaluation moves beyond asking whether a provider offers single tenancy. It examines what the offering actually includes and how it will operate.

Five questions provide a starting point:

  1. What is dedicated, and what remains shared? Ask the provider to identify the application, database and workload resources within the dedicated environment, along with any remaining dependencies.
  2. How are security controls scoped to our institution? Review the approach to networking, encryption, identity, monitoring and access oversight, including the scope available for incident investigation.
  3. What can be configured, and under what terms? Clarify integration options, customization boundaries, associated costs and responsibility for ongoing support.
  4. How will updates be coordinated? Establish the operating model for change scheduling rather than assuming that a dedicated environment gives the institution unrestricted control.
  5. What investment and operational support does the deployment require? Understand how resources will be provisioned, how the environment will be supported and how the arrangement fits the institution’s vendor-risk assessment.

The answers matter more than the label. They turn “single tenant” from an architectural description into a deployment an institution can evaluate.

Built for independent firms and institutional requirements

Wealth.com’s approach is to support different deployment needs without making every customer adopt the same infrastructure model.

For most customers, that means using our multi-tenant environment to bring estate and tax planning into the advisory relationship.

For institutions requiring a dedicated deployment, it means separate application and database environments, isolated compute resources, firm-specific security controls and an agreed approach to configuration, change management and operational support.

Wealth.com is the only estate and tax planning provider to offer single-tenant capabilities. Our enterprise experience also includes successful deployments at three of the top five U.S. banks.

Our philosophy is straightforward: an independent advisory firm should not need a bank’s deployment model to deliver sophisticated planning. A bank should not have to set aside its institutional requirements to access the same planning capabilities.

The right technology partner should understand both.

Enterprise planning is about what the software enables. At institutional scale, it is also about how that software fits the organization.

Explore Wealth.com for Enterprise

Talk with our team about your institution’s estate and tax planning needs, deployment requirements and operating model. Learn more at https://www.wealth.com/for-enterprises/.

The Q4 Planning Playbook: Tax and Estate Conversations to Have With Every Client

A strong year-end plan starts before year-end feels urgent.

October still gives advisors time to find the issues. November creates room to compare options and make decisions. By December, the work needs to move from recommendation to execution.

Too often, all three phases are compressed into one year-end client meeting agenda. The advisor reviews performance, asks about charitable giving, checks required minimum distributions, raises tax-loss harvesting, mentions outdated estate documents, and sends a long follow-up list. The conversation may be comprehensive, but the window to act is already closing.

Effective Q4 financial planning follows a sequence:

October
Reveals
November
Decides
December
Executes

That sequence turns the annual review from a retrospective meeting into a coordinated tax and estate planning process.

What should a year-end planning checklist for advisors include?

A year-end planning checklist for advisors should cover projected income and tax liability, withholding and estimated payments, realized and unrealized gains and losses, retirement distributions, charitable giving, family gifts, estate documents, beneficiary designations, asset titling, trust funding, and material life changes.

The checklist becomes more useful when it is spread across three stages instead of treated as a single meeting:

October
Reveal

Primary objective

Build the baseline and identify gaps.

Client outcome

A prioritized planning inventory.

November
Decide

Primary objective

Model tradeoffs and approve recommendations.

Client outcome

A documented action plan.

December
Execute

Primary objective

Complete, confirm, and record each action.

Client outcome

A closed-loop implementation record.

This structure gives the advisor, client, CPA, attorney, and other specialists enough time to work from the same information without forcing every decision into the final weeks of the year.

Before the first Q4 meeting: Build the client’s current planning record

The quality of a Q4 meeting depends on what is known before it begins. If the advisor spends October gathering documents one at a time, November becomes the discovery phase and December becomes a scramble.

Before the first meeting, collect or confirm:

  • The most recently filed federal and state tax returns
  • Current-year income, withholding, and estimated tax payments
  • Expected bonuses, business income, equity compensation, or liquidity events
  • Realized gains and losses, plus significant unrealized positions
  • Retirement contributions, distributions, and required minimum distribution status
  • Charitable giving and family gifting completed or contemplated during the year
  • Current estate documents and the date of the last review
  • Beneficiary designations and ownership of major assets
  • Trusts, entities, insurance policies, and business interests
  • Family, employment, residency, health, or ownership changes
  • Open recommendations from the prior annual review

For clients who requested an extension, October may also be the first time the completed prior-year return is available for planning. For 2026, the federal filing deadline for most individual taxpayers with an extension is October 15. An extension to file did not extend the original deadline to pay. See IRS filing guidance.

The filed return should not be treated as historical paperwork. It is the starting data set for the next recommendation.

October: Reveal the full planning picture

October is the diagnostic month. The advisor’s job is to establish what changed, where the client is likely to finish the year, and which decisions have a real deadline.

Start with the tax baseline

Compare the most recent return with current-year expectations. Look for changes in:

  • Salary, bonus, self-employment income, or business distributions
  • Interest, dividends, capital gains, and investment income
  • Stock option exercises, restricted stock vesting, or concentrated equity
  • Retirement contributions and distributions
  • Itemized deductions and charitable activity
  • State residency or multistate income
  • Withholding and estimated tax payments
  • Carryforwards, credits, or other items identified by the client’s tax professional

The goal is not to finalize the return in October. It is to create a credible current-year projection and identify the variables that could still change.

Run the estate alignment scan

Tax planning should not begin and end with the income tax return. Ask what changed in the client’s life and ownership structure during the year:

  • Was there a marriage, divorce, birth, death, or change in family relationships?
  • Did the client move to another state or buy property there?
  • Was a business formed, sold, recapitalized, or materially revalued?
  • Did the client inherit assets or begin supporting another family member?
  • Are the named fiduciaries and beneficiaries still appropriate?
  • Were previously created trusts actually funded?
  • Do beneficiary designations and account titles match the estate plan?
  • Has the client’s expected estate tax exposure materially changed?

An annual estate review does not require the advisor to reopen every document each year. It does require enough visibility to recognize when a legal review is warranted.

Triage by deadline, impact, and dependency

Not every planning opportunity belongs on the Q4 action list. Rank each item using three questions:

1
Deadline

Must the action occur during the current calendar year?

2
Impact

Is the potential benefit or avoided risk material to the client?

3
Dependency

Does execution require a CPA, attorney, custodian, trustee, valuation professional, or family decision?

The output from October should be a short planning inventory divided into three categories: act this year, prepare for next year, and monitor.

That clarity protects the client from an overwhelming checklist and protects the advisory team from treating every idea as equally urgent.

November: Decide which strategies belong in the plan

November is the decision month. The baseline is established, the planning gaps are visible, and there is still time to evaluate tradeoffs before operational deadlines take over.

Model the tax alternatives

Depending on the client, the November analysis may include:

  • Roth conversion scenarios
  • Capital gain or loss harvesting
  • Charitable gifts of cash or appreciated assets
  • Qualified charitable distributions for eligible IRA owners
  • Income, deduction, or business expense timing
  • Withholding or estimated tax adjustments
  • Retirement plan contribution opportunities
  • Equity compensation exercises or sales
  • State residency and multistate tax considerations
  • Business owner compensation, distributions, or liquidity events

The recommendation should quantify more than the current-year tax result. A decision that lowers this year’s tax bill may increase future exposure, reduce liquidity, alter the investment plan, or create an unintended estate consequence.

Connect every tax recommendation to the estate plan

Tax and estate decisions are connected by ownership, cash flow, and time. The advisor should make those connections explicit.

Tax decisionPotential estate or planning consequenceQuestion to resolve
Roth conversionChanges current income, future retirement balances, and the assets heirs may inheritDoes the long-term family benefit justify the current tax cost?
Gift of appreciated assetsReduces the donor’s ownership and may shift future appreciationIs the transfer consistent with the client’s liquidity and inheritance goals?
Charitable contributionChanges cash flow, portfolio composition, and the assets remaining for familyIs the giving strategy coordinated with the broader legacy plan?
Capital gain or loss harvestingChanges taxes, basis, and portfolio exposuresDoes the tax action support the investment plan rather than distort it?
Business income or equity decisionCan affect tax liability, valuation, liquidity, and ownership concentrationDoes the personal tax strategy align with business succession and estate planning?

This is where integrated year-end planning becomes more valuable than a collection of separate calculations. The advisor is not simply asking, “How much tax could this save?” The advisor is asking, “What else changes if the client does it?”

Finalize the estate actions

November is also the time to determine whether any estate-related action should be completed before year-end:

  • Annual gifts to family members or trusts
  • Trust contributions and related administrative requirements
  • Charitable gifts that support the client’s tax and legacy goals
  • Beneficiary designation changes
  • Account or property retitling
  • Funding of an existing revocable or irrevocable trust
  • Updates prompted by a family, fiduciary, residency, or ownership change
  • Insurance ownership or beneficiary reviews
  • Business succession, buy-sell, or valuation work that requires specialist involvement

For 2026, the federal gift tax annual exclusion is $19,000 per recipient, with separate exclusions generally available to each spouse. Gifts of future interests and gift splitting can involve additional rules and filing requirements, so the client’s attorney and tax professional should guide the structure and reporting. See the IRS gift tax FAQs.

The fact that an annual exclusion is available does not mean every client should use it. Gifting decisions should begin with the client’s financial security, intent, family dynamics, and long-term estate strategy.

End November with a decision record

Every approved recommendation should identify:

  • The action to be completed
  • Why it supports the client’s goals
  • The amount or key assumption involved
  • The person responsible
  • The required specialist or custodian
  • The operational deadline
  • The evidence that will confirm completion

The advisor should also record recommendations the client declined or deferred. That preserves context and gives next year’s annual client review framework a much stronger starting point.

December: Execute, confirm, and close the loop

December should not be the month when the planning team first discovers a complex gift, outdated trust, missing valuation, or unresolved family decision.

It should be the month when approved actions move through a controlled execution process.

Use an execution calendar, not one final deadline

Many strategies may have a December 31 tax deadline, but custodians, charities, payroll teams, attorneys, trustees, and financial institutions often require earlier processing. Create internal deadlines that leave room for rejected paperwork, missing signatures, market closures, asset valuation, and client hesitation.

A practical cadence is:

Early December

Reconfirm assumptions, secure final client approval, and initiate transfers or paperwork.

Mid-December

Verify processing, signatures, valuations, notices, and specialist deliverables.

Final business days

Resolve exceptions and confirm completion. Avoid introducing strategies that cannot be implemented responsibly.

Confirm the year-end tax actions

Depending on the client’s plan, the advisor and tax professional may need to confirm:

  • Required minimum distributions have been completed
  • Qualified charitable distributions have reached the intended charity
  • Charitable contributions intended for the current tax year have been made and can be substantiated
  • Approved Roth conversions have been processed
  • Planned gain or loss transactions have been completed
  • Withholding and estimated payment decisions have been implemented
  • Retirement plan contributions subject to a calendar-year deadline have been addressed
  • Business, equity compensation, or liquidity actions have been completed as intended

Most retirement account owners subject to required minimum distributions must receive them by December 31, although special timing rules can apply to a first RMD. See the IRS RMD guidance. Charitable contributions generally must be paid in cash or property before the close of the individual’s tax year to be deductible for that year, and substantiation rules apply. See IRS Publication 526.

Confirm the estate actions

Estate-related completion may include:

  • Signed estate planning documents
  • Confirmed beneficiary changes
  • Completed account or property retitling
  • Verified trust funding
  • Completed family or trust gifts
  • Required trust notices and administrative records
  • Updated insurance ownership or beneficiaries
  • Stored copies of executed documents and valuation materials
  • A clear list of items that remain with the attorney, CPA, trustee, or client

Execution is not complete because a form was sent. It is complete when the advisory team can verify the intended result.

A repeatable annual client review framework

The same seven-part framework can anchor fourth quarter advisor planning across the client base:

Update: What changed in the client’s life, family, income, assets, entities, and residency?

Baseline: Where is the client likely to finish the year for tax and estate purposes?

Identify: Which opportunities, gaps, and risks deserve attention?

Model: How do the available strategies change taxes, liquidity, ownership, and long-term outcomes?

Decide: Which recommendations does the client approve, decline, or defer?

Execute: Who owns each action, and how will completion be verified?

Carry forward: What should be monitored or prepared in the next calendar year?

The framework stays consistent, but the agenda should change with the client.

Retirees

Prioritize RMDs, qualified charitable distributions, withholding, Medicare-related income considerations, Roth conversions, beneficiary designations, and trust alignment.

Business owners

Prioritize projected business income, estimated payments, retirement contributions, valuation changes, liquidity, succession, buy-sell agreements, and the ownership of business interests.

Executives and equity-compensated clients

Prioritize vesting, option exercises, withholding, concentrated stock, gain recognition, charitable transfers, liquidity, and the estate impact of growing equity value.

Families accumulating wealth

Prioritize changing income, workplace benefits, education funding, insurance, guardians, beneficiary designations, powers of attorney, and foundational estate documents.

High-net-worth and multigenerational families

Prioritize trust funding, gifting, charitable planning, entity ownership, insurance, estate tax exposure, fiduciary decisions, and coordination across generations.

“Every client” should not mean “the same checklist for every client.” It should mean that every client receives a consistent planning process built around the issues that actually apply to them.

Why unified tax and estate workflows matter most in Q4

Fragmented planning creates repeated handoffs. A tax return is uploaded into one system, projections are built in another, estate documents sit in a separate vault, and execution is tracked through email or spreadsheets. Each handoff creates another opportunity to lose assumptions, duplicate work, or miss the connection between a tax recommendation and an estate outcome.

A unified workflow allows the advisor to move through one continuous process:

Review tax returns, estate documents, ownership, and household information.
Establish a current tax and estate baseline.
Identify and model planning opportunities.
See how a recommendation affects taxes, liquidity, estate distributions, and family outcomes.
Present a clear recommendation to the client.
Coordinate the attorney, CPA, custodian, or other specialist.
Track execution and preserve the decision record for the next review.

Wealth.com brings tax and estate planning into one advisor-led platform. Advisors can securely ingest tax documents such as Form 1040 and W-2, establish a historical baseline, build forward-looking projections, model strategies, and connect those decisions to estate documents, legal structures, and client reporting. Explore Wealth.com Tax Planning.

That continuity is particularly valuable in Q4. Advisors can move from review to recommendation to execution without rebuilding the client’s story every time the work crosses from tax planning into estate planning.

The goal is not a longer checklist

The best Q4 tax and estate strategies are not the ones that create the most activity. They are the ones that help the client make the right decisions while there is still time to complete them.

October reveals the planning picture. November turns analysis into decisions. December turns those decisions into completed work.

That is what moves Q4 financial planning beyond an annual review. It becomes an operating system for proactive advice.


Ready to connect tax planning, estate strategy, and execution in one continuous workflow?


See how Wealth.com helps advisors plan with greater clarity and confidence.

Frequently asked questions about Q4 financial planning

When should advisors begin year-end planning?

Advisors should begin collecting data and identifying planning issues by October, or earlier for clients with complex tax, estate, business, or charitable needs. Waiting until December can leave too little time for modeling, specialist review, signatures, transfers, and custodial processing.

What should be included in a year-end client meeting agenda?

The agenda should address material life changes, projected income and tax liability, withholding and estimated payments, investment gains and losses, retirement distributions, charitable giving, family gifts, beneficiary designations, estate documents, trust funding, and open implementation items.

Which planning actions may need to be completed by December 31?

Depending on the client, year-end actions may include required minimum distributions, charitable contributions, Roth conversions, capital gain or loss transactions, certain retirement plan contributions, family or trust gifts, and other tax-sensitive transfers. Operational deadlines may occur before December 31, and clients should confirm requirements with their tax, legal, and financial professionals.

How should tax and estate planning be coordinated?

Each tax recommendation should be evaluated for its effect on liquidity, asset ownership, estate value, beneficiaries, and long-term family outcomes. Each estate action should also be evaluated for its current and future tax consequences. Advisors can help coordinate the client’s attorney, CPA, and other specialists around one set of facts and goals.

Does every client need the same Q4 planning checklist?

No. Every client should receive the same disciplined review process, but the specific agenda should reflect the client’s age, income, assets, family, business interests, estate complexity, and planning goals.


This material is for educational purposes only and is not intended to provide legal, tax, accounting, or investment advice. Clients should consult qualified professionals regarding their individual circumstances.

The Estate and Tax Planning Conversations Advisors Should Have With Every New Parent

New parents leave the hospital with feeding schedules, pediatric appointments, insurance forms, and very little sleep. A will rarely makes the first-week list.

Yet the birth or adoption of a child changes nearly every part of a family’s financial and estate plan. There is now someone who depends on the parents for care, income, housing, and long-term support. The family may have new tax benefits, new insurance needs, new account beneficiaries, and a new reason to decide who should act if a parent cannot.

This is why estate planning for new parents should not begin with a stack of documents or a lecture about worst-case scenarios. It should begin with a calm conversation and a clear sequence.

For advisors, the opportunity is to help new parents move from chaos to clarity. That means identifying the few decisions that cannot wait, organizing the decisions that can, and coordinating the family’s estate, tax, insurance, education, and document workflows without asking exhausted clients to manage the process themselves.

What estate planning should new parents complete?

At a minimum, new parents should name preferred guardians in a will, decide who would manage inherited assets for a minor child, update wills and trusts, review beneficiary designations, reassess life and disability insurance, update financial powers of attorney and healthcare directives, evaluate available tax benefits, consider a 529 plan, and organize critical family records. The exact documents and strategies depend on state law, family structure, benefits, and finances, so legal and tax professionals should be part of the process.

The advisor’s job is not to finish every item in one meeting. It is to establish order, ownership, and momentum.

A new parent financial planning checklist that respects the moment

The most useful framework is phased. It gives every task a time, an owner, and a clear outcome.

TimingPlanning conversationDesired outcome
Before birth or during the first 30 daysBenefits, tax baseline, identity documents, emergency contactsThe child is added to the family’s administrative and financial systems
First 30 to 90 daysGuardianship, wills, trusts, executors, trustees, parental incapacity documentsThe parents’ intentions are documented and ready for attorney review or execution
First three to six monthsBeneficiaries, insurance, 529 plan, cash flow, tax projectionAccounts and protection strategies align with the estate plan
Annually and after every major changeGuardians, fiduciaries, coverage, beneficiaries, documentsThe plan remains current as the family and its finances evolve

This sequence also gives advisors a repeatable life event estate planning workflow. Instead of waiting for clients to ask about a will, the advisor can recognize a birth, adoption, pregnancy, or fertility journey as a planning trigger and open the right conversations at the right pace.

Conversation 1: Guardianship designation for new parents

For many parents, the hardest estate planning question is also the most important: Who should care for the child if both parents die?

A guardianship designation for new parents is not simply a request to name the nearest relative. The advisor can help the couple work through the decision without trying to make it for them.

Useful questions include:

  • Who shares the parents’ values and approach to caregiving?
  • Does the proposed guardian have the health, capacity, and willingness to serve?
  • Where does the person live, and would the child need to move?
  • Could siblings remain together?
  • What would the choice mean for school, community, culture, and religious upbringing?
  • How would the guardian’s own children or household be affected?
  • Who is the backup if the first choice cannot serve?

Parents should speak with the proposed guardian before putting a name in a document. They should also revisit the choice as relationships, health, locations, and family circumstances change.

The advisor should make one legal boundary clear: naming a guardian in a will records the parents’ preference, but it does not bypass the court. Appointment procedures and standards vary by state. For example, New York Courts explains that a person named in a will becomes the legal guardian only after a judge approves the guardianship. An estate planning attorney can advise the family on the rules that apply where they live.

Separate the caregiver from the money manager

New parents sometimes assume that the guardian must also manage the child’s inheritance. That is not always the best structure.

The person best suited to raise a child may not be the person best suited to administer investments, follow trust terms, maintain records, and approve distributions. A trust can allow parents to name a trustee for financial responsibilities and a guardian for day-to-day care.

That separation can add checks and balances, but it also requires cooperation. Advisors can help parents discuss how the guardian and trustee would communicate, what financial support the guardian may need, and how the plan should cover housing, childcare, education, healthcare, travel, and other costs.

Conversation 2: Wills for new parents and the role of a trust

Even parents who already have estate documents may have plans that were signed before the child was born, before marriage, or before a major financial change. Wills for new parents should be reviewed to confirm that the child, guardian nominations, fiduciaries, and distribution plan are handled intentionally.

The core conversation should cover:

  • Who will serve as executor or personal representative?
  • Who should serve as guardian, and who is the alternate?
  • Should a trustee manage assets for the child?
  • At what ages or milestones should the child receive control?
  • What distribution standard should support health, education, maintenance, and other needs?
  • How should the plan address additional children, children from a prior relationship, adoption, or assisted reproduction?
  • Does the family need a revocable trust or other trust planning in addition to a will?

Leaving assets directly to a minor can create legal and administrative complications because a child generally cannot manage the property. A properly designed trust may provide clearer instructions, longer-term management, and more flexibility than an outright inheritance. The appropriate structure depends on state law, asset ownership, tax considerations, and family goals.

Advisors do not need to practice law to add value here. They can help the clients define the desired outcome, inventory the relevant assets, identify unanswered questions, and give the estate planning attorney a clean planning brief. This reduces repetition and keeps the family from translating the same facts across separate conversations.

Conversation 3: Beneficiary designations must match the plan

A new will does not automatically update a retirement account or life insurance policy. That distinction is easy to miss and can materially change who receives an asset.

The IRS notes that assets with beneficiary designations, including retirement accounts and life insurance, generally pass under those designations rather than under a will. Advisors should therefore lead a beneficiary review across:

  • Employer retirement plans
  • IRAs and Roth IRAs
  • Life insurance and annuities
  • Health savings accounts
  • Transfer-on-death and payable-on-death accounts
  • Equity compensation or employer death benefits
  • Any account with a primary or contingent beneficiary field

For many married couples, a spouse remains the primary beneficiary and the child, or an appropriately drafted trust for the child’s benefit, may be considered as a contingent beneficiary. But there is no universal answer. Retirement plan rules, spousal rights, tax treatment, trust language, and the child’s age all matter. The IRS also explains that some retirement plans require particular beneficiaries, such as a spouse or child, under the plan’s terms.

The advisor’s workflow should include three distinct steps:

  1. Identify the current designation.
  2. Coordinate the intended change with the estate attorney, tax professional, plan administrator, and insurance professional as appropriate.
  3. Confirm that the custodian or carrier accepted the completed change.

The third step is crucial. A recommendation is not execution, and a submitted form is not proof that the account was updated.

Conversation 4: A new parent insurance review

Life insurance often becomes more important when a child arrives because a parent’s future income and unpaid caregiving now support another person. A thoughtful new parent insurance review should examine both parents, even if only one earns a paycheck.

The analysis may include:

  • Income replacement for the surviving household
  • Mortgage, rent, and other debts
  • Childcare and household support
  • Education goals
  • Healthcare and final expenses
  • Time away from work for the surviving parent
  • Business ownership or personal guarantees
  • Existing group and individual coverage
  • Coverage duration, policy type, cost, and insurability

The economic value of a stay-at-home parent should not be ignored. Replacing childcare, transportation, household management, and other responsibilities can be expensive, and a surviving parent may need to reduce work hours.

Beneficiary structure is part of the insurance review. Naming a minor child directly can create difficulties because insurers generally do not pay proceeds directly to minors. The National Association of Insurance Commissioners advises families with minor children to consider a carefully established trust with guidance from an attorney or tax advisor.

Disability and income protection also belong in the conversation. The risk is not limited to death. A prolonged illness or injury can reduce income while increasing care costs. Advisors can coordinate with a licensed insurance professional to review employer benefits, waiting periods, coverage definitions, benefit amounts, and gaps.

Conversation 5: Tax planning and 529 plan setup advisor guidance

A child can change a household’s tax return, payroll withholding, employee benefits, childcare costs, and savings priorities. The advisor should review the new facts rather than assume the family will automatically receive a particular credit or deduction.

The tax conversation can include:

  • Eligibility for the Child Tax Credit
  • Eligibility for the Child and Dependent Care Credit
  • Dependent care benefits available through an employer
  • Health savings or flexible spending account elections
  • Payroll withholding and estimated taxes
  • Adoption-related tax considerations, if applicable
  • Filing status and household changes
  • The child’s Social Security number and other documentation needed for tax reporting

Eligibility rules, income limits, and required records vary. The IRS provides a current overview of tax benefits for parents and families, and a tax professional can help determine which provisions apply to the household.

When should parents open a 529 plan?

There is no mandatory deadline for opening a 529 plan. The right time is when the family has adequate cash flow, an emergency reserve, and a savings strategy that supports its broader priorities.

Strong 529 plan setup advisor guidance should address:

  • The education goal and expected funding sources
  • The account owner and successor owner
  • The child named as beneficiary
  • State plan features and possible state tax benefits
  • Contribution cadence and investment selection
  • Coordination with grandparents and other relatives
  • How education savings fits alongside retirement, insurance, and debt goals

According to the SEC’s Investor.gov 529 plan guidance, earnings used for qualified education expenses generally are not subject to federal income tax, while state tax treatment and incentives vary. That variability is one reason an advisor should compare the family’s home-state plan with other options rather than defaulting to the first account presented.

The 529 conversation should not crowd out the protection work. A college account is useful, but it cannot substitute for a will, guardian nomination, adequate insurance, or an emergency fund.

Conversation 6: Update the parents’ incapacity documents

New parents naturally focus on what would happen to the child if they died. They should also decide what happens if either parent is alive but unable to act.

That means reviewing or creating:

  • A durable financial power of attorney
  • An advance healthcare directive
  • Healthcare agent and backup agent designations
  • Any state-specific medical privacy authorization
  • Instructions for accessing critical financial, legal, and medical information

The agents chosen years earlier may no longer be the right people. A parent may also want to name backups who can act if a spouse is unavailable at the same time.

These documents protect the whole family. If a parent is incapacitated, another trusted person may need to pay bills, communicate with insurers, manage accounts, make medical decisions, or coordinate care. The correct documents and signing requirements vary by state, so attorney review is essential.

Conversation 7: Family document organization

Planning fails when the right documents exist but no one can find them.

New parents often receive important records at different times and from different institutions. Effective family document organization gives the household one reliable system for physical originals, digital copies, ownership, and renewal dates.

Records for the child

  • Certified birth certificate
  • Social Security card or Social Security number confirmation
  • Passport, if obtained
  • Adoption, citizenship, or parentage records, when applicable
  • Health insurance enrollment and identification cards
  • Immunization and important medical records
  • Childcare, school, and emergency contact information

Estate and financial records

  • Wills, trusts, and amendments
  • Guardian, executor, trustee, and agent contact information
  • Financial powers of attorney and healthcare directives
  • Life, disability, and health insurance policies
  • Current beneficiary confirmation statements
  • Retirement, investment, bank, and 529 account information
  • Property deeds, titles, and business ownership records
  • Contact information for the advisor, attorney, CPA, and insurance professional

Families should store certified originals in an appropriate secure physical location and keep organized digital copies for access and coordination. A digital copy does not replace an original when an agency requires certified evidence. For example, the U.S. Department of State requires physical citizenship evidence for a passport application and does not accept electronic copies.

The family should also know how to obtain or replace key records. Under the Social Security Administration’s Enumeration at Birth process, a parent may request the newborn’s Social Security number through the birth registration process. If a family plans international travel, the State Department has a separate passport process for children.

A single, secure home for the planning record

Wealth.com’s Vault gives advisors and clients a secure place to organize critical estate planning documents and supporting records. With encrypted, permission-based access, the Vault can help a family maintain accessible copies of wills, trusts, directives, policies, account confirmations, birth certificates, and other planning materials while preserving the advisor’s view of what is complete and what is missing.

The practical value is continuity. The estate plan, insurance review, beneficiary confirmations, tax records, and family documents no longer live in separate email threads, paper folders, and portals. The advisor and family can work from a shared planning record, subject to the permissions the client chooses.

The Vault should complement, not replace, secure storage of originals. The best system tells the family both where the original is kept and where an accessible copy can be found.

The advisor’s role: Stabilize, protect, align, organize

The advisor does not need to solve every legal, tax, and insurance question personally. The advisor does need to keep the process coherent.

A four-part workflow can make that role concrete:

1. Stabilize

Confirm benefits enrollment, tax and identity documentation, near-term cash flow, emergency reserves, and immediate administrative deadlines.

2. Protect

Address guardian nominations, wills, trusts, incapacity documents, life insurance, and disability coverage with the appropriate professionals.

3. Align

Make sure account ownership, beneficiary designations, insurance beneficiaries, 529 decisions, and the estate plan point toward the same intended outcome.

4. Organize

Store final documents and confirmations, record where originals are located, assign follow-up tasks, and establish an annual review date.

For every recommendation, the advisor should capture:

  • The decision to be made
  • The professional responsible for advice or drafting
  • The person responsible for execution
  • The due date
  • The evidence that confirms completion

This is how an advisor becomes the calm, organized professional a new family needs. The value is not another checklist. It is the confidence that every important decision has a place, every task has an owner, and every completed document can be found.

Make new parent planning an annual conversation

The first plan is only the starting point. Advisors should schedule a focused review at least annually and after any major family or financial change, including:

  • The birth or adoption of another child
  • A move to another state
  • Marriage, divorce, or a change in family structure
  • A change in the proposed guardian’s circumstances
  • A new job, benefit plan, business, or equity award
  • A home purchase or major debt change
  • A meaningful increase in income or net worth
  • The expiration or replacement of insurance coverage
  • A change in tax or estate law

The annual meeting does not need to recreate the original project. It should confirm that the people, documents, accounts, and protection strategies still align.

From chaos to clarity

New parents rarely need more information. They need someone to create order.

By sequencing the work across guardianship, wills and trusts, beneficiaries, insurance, taxes, education funding, healthcare directives, and documents, advisors can make a difficult planning moment manageable. They can also coordinate the attorney, tax professional, insurance professional, and family around one set of facts and one shared outcome.

Wealth.com helps advisors turn those conversations into an integrated planning process. Its advisor-led platform supports estate document creation, collaboration, task management, and secure document organization, helping families move from intention to execution without losing context. Explore Wealth.com’s platform or request a demo.

Frequently asked questions

Why is estate planning important for new parents?

Estate planning lets parents record guardian preferences, choose who will manage assets for a minor child, coordinate beneficiaries, and authorize trusted people to act during incapacity. Without a plan, state law and court procedures may determine outcomes the parents could have addressed in advance.

How should new parents choose a guardian?

Parents should consider values, caregiving ability, health, location, household dynamics, willingness, and the effect on the child’s community and siblings. They should speak with the proposed guardian, name an alternate, and work with an attorney to document the nomination under applicable state law.

Should a minor child be named directly as a life insurance beneficiary?

Often, naming a minor directly creates administrative problems because an insurer generally will not pay proceeds directly to the child. Parents should ask an estate planning attorney and insurance professional whether an appropriately drafted trust, custodian, or other structure fits their plan.

Do beneficiary designations override a will?

In general, assets such as retirement accounts and life insurance pass under the beneficiary designation on file, not under the will. Plan rules, spousal rights, account type, and state and federal law can affect the result, so families should coordinate changes with their professional team.

When should new parents open a 529 plan?

There is no single deadline. Parents can consider opening a 529 plan when their cash flow, emergency reserve, insurance, retirement savings, and other priorities support education funding. An advisor can help compare plans, state tax considerations, ownership, funding, and investment choices.

What documents should new parents keep in a secure digital vault?

Useful records include copies of wills, trusts, powers of attorney, healthcare directives, insurance policies, beneficiary confirmations, birth certificates, Social Security records, passports, 529 statements, account information, and professional contacts. Certified originals should remain in secure physical storage when the issuing authority requires them.

This material is for educational purposes only and is not legal, tax, or investment advice. Estate planning, guardianship, tax, insurance, and account rules vary by jurisdiction and circumstance. Clients should consult qualified legal, tax, insurance, and financial professionals before taking action.
Estate and Tax Planning Inside Claude: What Advisors Can Do Starting Today

Wealth.com is the estate and tax planning launch partner for Claude for Financial Advisors, which Anthropic announced today.

We also released a Wealth.com connector for Claude, built on the Model Context Protocol (MCP), the open standard Anthropic created for connecting AI applications to outside systems and data. Firms already on the Wealth.com platform can enable it in their existing Claude workspace, under their own firm AI policies, at no additional cost from Wealth.com.

This post covers what that means in practice: where answers to estate and tax questions come from, four real-world advisor workflows transformed by this approach, and how to learn more.

Where the answers live

Estate and tax questions have defined answers, and those answers sit in specific places.

What a trust says about the disposition at the first spouse’s death is set by an executed document. Who holds authority under a health care directive is set by that directive. Whether an account is titled in a trust is a fact in a firm’s records. What a $200,000 Roth conversion produces for a specific household in a specific tax year is arithmetic under that year’s federal and state rules.

Three sources hold all of that: the executed documents, the firm’s records, and a tax calculation engine loaded with current federal and state data. None of them are public, and none of them are reachable by an AI assistant on its own. That is precisely the problem MCP was built to solve, and it is why we built on it.

Wealth.com holds all three, and this integration connects them.

What each side brings

Claude reads and reasons across a client’s documents, records, and tax figures. An advisor can ask a question in the language they would use with a colleague, across several hundred pages of documents, and follow the answer wherever it leads. They can hold a line of inquiry across a dozen turns, move from an estate question to a tax question without switching tools, and follow their own thinking rather than a navigation tree someone else designed. Conversation becomes the natural surface for working through what matters.

Wealth.com brings the records and tax engine those answers come from.

  • Document intelligence with page-level citations.
    Locating the provision that governs distributions at a specific age inside a 60-page restatement is work we have built specifically for estate documents. Every answer comes back with the page it came from, so an advisor can work from the provision itself rather than from a description of it.
  • A deterministic tax calculation engine.
    Given the same inputs and the same tax year, it returns the same figures every time, using published federal and state tax data.
  • The firm’s records, with their context intact.
    Titling, beneficiary designations, and the relationships between accounts, trusts, and individuals are preserved, including where those relationships have not yet been established.

Neither piece does the job alone. Claude works through a question the way an advisor would, and Wealth.com ties each answer to its source.

Four walkthroughs

1. Preparing for a prospect meeting from a stack of documents

An advisor has a first meeting with a prospective client in an hour. The prospect sent over a revocable trust executed in 2016, a first amendment from 2021, a will, a durable power of attorney, and a health care directive. That is a few hundred pages, most of it boilerplate, none of it read.

The advisor brings the documents into Claude and asks, in plain language:

  • What happens at the first spouse’s death?
  • Does the survivor have full control of the assets, or does the trust split into subtrusts?
  • When do the children gain control of their inheritance?
  • Who is the successor trustee, and in what order?
  • Who can make health care decisions if the client cannot?

Each answer comes back with a citation to the page it came from, including whether the governing language sits in the original trust or in the 2021 amendment, which is exactly the kind of thing a fast read misses. Ask for the disposition structure and it returns as a flowchart.

The advisor walks into the meeting with three informed questions instead of a request to send more paperwork.

2. Finding the provisions worth raising before the client raises them

Same documents, but a different question. Instead of asking what the plan does, the advisor asks what is worth a conversation.

This surfaces the things that tend to sit unexamined in an estate plan for years:

  • A co-trustee requirement nobody flagged, which means the person the client believes can act alone cannot.
  • A beneficiary holding authority over future trustee appointments, which changes who controls the trust over time.
  • A signature page that may never have been executed on an amendment the family believes is in force.
  • Distribution ages that do not match what the client described in conversation.

None of these are unusual. All of them are the difference between a review meeting where the advisor is reporting and a review meeting where the advisor is advising. Each one comes back with a citation, so the advisor can read the provision before deciding whether to raise it.

3. Understanding an existing client household

For clients already on the platform, an advisor can work through the broader financial picture the same way: what the household owns, how each asset is titled, where wealth is concentrated, and how beneficiary designations are recorded.

The part that matters more than people expect is what Wealth.com preserves about the gaps. If a relationship between an account, a trust, and an individual has not been established in the firm’s records, the answer says so rather than filling the hole with an assumption.

An advisor asking, “Is this account titled in the trust?” needs to be able to distinguish between “no” and “we do not have that recorded.” Those two answers lead to completely different next steps.

4. Working through a tax planning conversation

An advisor pulls up a summary of a client’s filed return covering income, deductions, total tax, and federal and state tax rates. Then the conversation moves to what happens next:

  • Roll the filed return forward under the applicable year’s tax law to see what the same income profile produces under current rules.
  • Evaluate a Roth conversion at several amounts to find where the marginal cost stops being worth it.
  • Back out a one-time event, such as a business sale or a concentrated position liquidation, to get a baseline that reflects what the household actually looks like going forward.
  • Build an initial estimate for a prospect who has not shared a return yet, using available financial information and stated assumptions, with those assumptions visible in the output.

Every figure in those scenarios comes from our calculation engine and the applicable federal and state tax data.

How to tell where an answer came from

Every figure the connector returns is attributed to one of three sources:

  1. The firm’s record, meaning data the firm maintains in Wealth.com.
  2. A cited page of a client document, with the page reference included.
  3. The calculation that produced it, with the tax year and rules applied.

Each also carries the date through which the information is current, so an advisor can tell whether they are looking at something reconciled last week or last quarter.

What this does not do

It does not draft estate planning documents, and it does not give legal advice. Document analysis tells an advisor what a plan currently says. Changing what it says is legal work.

It does not file tax returns or give tax advice. The scenarios are planning estimates built on stated assumptions, and they belong in a conversation with the client’s tax professional.

It does not know what is not in the documents or the firm’s records. If a trust was amended and the amendment was never uploaded, no system reading the uploaded documents will know about it.

See it live at Future Proof

Wealth.com co-founder and chief growth officer Tim White and Drew Parker, financial services lead at Anthropic, are demonstrating the integration at booth 235 at Future Proof Festival in Huntington Beach on .

To learn more or get started, visit claude.wealth.com.

Wealth.com Brings Estate and Tax Planning Into Claude for Financial Advisors

NEW YORK, NY — September 14, 2026 — Wealth.com, the leading estate and tax planning platform for wealth management firms, today announced it is a launch partner for Claude for Financial Advisors.

Estate and tax planning demand a level of precision that few advisor workflows do. Questions about what a trust provides, who holds authority under a health care directive, or what the financial impact of a tax strategy would be must be grounded in executed documents, applicable law and validated quantitative analysis. Wealth.com brings that foundation into Claude for Financial Advisors, combining Claude’s reasoning with Wealth.com’s estate and tax engines. Advisors can explore a client’s situation naturally while relying on precise, source-grounded insights and figures for the decisions that follow.

“Estate and tax planning require advisors to bring together an enormous amount of information before they can have a meaningful conversation with a client,” said Rafael Loureiro, chief executive officer and co-founder of Wealth.com. “Together with Anthropic, we’re giving advisors a more intuitive way to work with that information. By bringing Wealth.com’s planning intelligence into Claude and making additional capabilities available through our connector, advisors can move from information to insight within the AI workflows they increasingly use every day.”

One of the most immediate applications is preparing for a client or prospect meeting. An advisor can bring a prospect’s estate documents into Claude and ask questions in plain language: What happens at the first spouse’s death? When do children gain control of their inheritance? Who can make health care decisions if the client cannot? Wealth.com performs the underlying document analysis, returns citations to the specific pages each answer comes from, and can render the disposition structure as a visual flowchart inside the conversation. Advisors then review and apply their judgment on what to do next.

The same analysis surfaces provisions an advisor would want to raise before a conversation: a co-trustee requirement, a beneficiary’s authority over future trustee appointments, or a signature page that may never have been executed. Instead of reading through lengthy documents across multiple systems, advisors can understand how a plan is structured and identify what needs discussion.

The capabilities extend to a household’s broader financial picture, including what they own, how assets are titled, where wealth is concentrated and how beneficiary designations are recorded. Wealth.com preserves the context behind that information, including where relationships among accounts, trusts and individuals are established in the firm’s records and where those relationships remain unconfirmed.

Advisors can bring the same conversational experience to tax planning. They can ask for a summary of a filed return covering income, deductions, total tax, and federal and state tax rates, then explore potential planning strategies. An advisor could roll a filed return forward under the applicable year’s tax law, evaluate a Roth conversion, account for a one-time gain that is not expected to repeat, or create an initial scenario for a prospect.

“As we built Claude for Financial Advisors, we focused on bringing the best of the advisor technology ecosystem directly into advisor workflows,” said Peter Nolan, head of asset and wealth management at Anthropic. “Wealth.com has established itself as the trusted estate and tax platform for wealth management firms, making its capabilities a natural complement to what we’re building. Together, we can give advisors a more complete set of tools to support the work they do for clients every day.”

Tim White, Wealth.com co-founder and chief growth officer, and Drew Parker, financial services lead at Anthropic, will demonstrate the integration live at the Wealth.com booth at Future Proof on Tuesday, Sept. 15 at 11 a.m. PT. Firms interested in enabling the integration can visit wealth.com/claude.

How to Evaluate Tax Planning Software: A Criteria-Driven Guide for Financial Advisors

Less than a decade ago, tax planning software for financial advisors barely existed as a category.

Today it is one of the fastest-growing segments of the advisor tech stack, for good reason. Tax planning touches nearly every dimension of a client’s financial life, and advisors who can deliver it at scale have a measurable competitive advantage.

Now in 2026, the tax planning category is well established and offers multiple credible options competing for a place in your tech stack.

More choice is beneficial for financial advisors, but it also means you need a solid understanding of what your firm needs and what each solution can provide to make the right decision.

The best tax software for your practice depends on what kind of planning you do, how complex your clients are, and what you need the software to actually connect to.

This article lays out the criteria that separate a capable tax planning tool from a comprehensive planning platform.

Start with Planning Orientation, Not Features

Before you start scanning through feature lists, start by asking, “What is this software designed to do?”

This is a better starting question than “What are all the things it can do?” because some software is built first and foremost for fast and accurate tax return review. Others, however, are designed for forward-looking scenario modeling that connects current decisions to multi-year outcomes.

These are different solutions solving different problems.

Beyond that starting point, you also want to understand whether the platform helps you model what happens next or only summarizes what already happened.

Advisors serving high-net-worth clients, business owners, or clients approaching retirement transitions need a solution that accurately summarizes a client’s current situation while also providing forecasted data that can support faster planning decisions.

Evaluate the AI Architecture, Not Just the AI Marketing

Every tax planning solution available to advisors now uses AI in some capacity. However, the use of AI can mean vastly different capabilities, and there are meaningful architectural differences advisors should understand before evaluating each solution.

OCR-based extraction reads tax documents and pulls figures accurately. It’s fast and reliable for reviewing tax returns, but it lacks the ability to understand context. Its job is primarily to assist with data management.

Generative AI, on the other hand, surfaces insights and recommendations from client data. The probabilistic nature of this implementation means that while powerful, it can also introduce variability in outputs. You can ask the same question with the same data twice and receive a different result each time.

The third application is purpose-built AI designed specifically for financial advisors, combining document intelligence with structured tax logic. Using a deterministic system, this approach can help identify planning opportunities, surface actionable recommendations, and connect tax strategy to outcomes across disciplines for multi-year tax modeling. It also offers explainable outputs that remain consistent over time.

Three questions to ask about any platform you’re reviewing:

  1. Can the platform read trust documents, corporate returns, and state filings, or only federal 1040s?
  2. How does the system handle conflicting data inputs?
  3. What is the accuracy standard for multi-year projections?

Scope Matters: Multi-Year, Multi-State, and Multi-Entity

Tax planning for an individual household is table stakes. Where tax planning software truly creates value today is by providing capabilities that help advisors navigate complex situations.

If you have clients with private investments, real estate holdings, S-corps, and LLCs, then you need a platform that can handle complexity without requiring manual workarounds.

Surveying the clients you serve and understanding what they need is one of the best ways to determine which tax planning solution fits your firm. If you have clients with complex financial situations, it’s almost certain that you’ll need a solution that supports multi-year scenario modeling, state tax projections, and income and distribution modeling across entity structures.

Practices that work with business-owning clients or family offices should weigh these capabilities heavily. A platform that handles W-2 households well but requires workarounds for pass-through entities will create a two-tier workflow: one process for simple clients and another for complex ones.

Make Client Experience Part of Your Evaluation

The foundation of great tax planning software is that it produces accurate analysis. But advisor software has another audience beyond the advisor: your clients.

Whether through generated reports or a shared screen during a meeting, your tax planning software will eventually be in front of your clients. That means the quality of the client experience should be part of your evaluation.

For example, can you update scenario modeling live as you adjust assumptions, or do you have to tell a client you’ll get back to them after a meeting? Does your tax planning software give clients a way to securely submit documents directly, or are you still relying on third-party solutions that break the workflow?

A client portal that serves as a digital home for both tax returns and estate documents creates a fundamentally different experience than PDF delivery. It shifts tax planning from a seasonal deliverable to an ongoing, visible part of the client relationship.

Integration Is the Multiplier

Possibly the most important consideration when evaluating tax planning software is understanding how the software fits into your larger financial planning process.

When it comes to a tax platform, the connection that matters is how well tax scenarios connect to estate outcomes. Significant planning opportunities, such as Roth conversions timed to estate transfers, charitable strategies structured around trust distributions, or business succession events that affect both income and estate tax implications, all require a view that spans both disciplines.

A siloed tax planning solution will always require the advisor to be the connector. What your firm needs instead is an integrated platform that makes the connection automatic.

A Framework to Use When Comparing Tax Planning Software

When comparing tax planning software, score each platform against these six criteria:

  1. Analysis capabilities. Does the platform only help you understand what already happened, or does it also model next steps? Software built around return review and software built around forward-looking scenario modeling serve different planning functions, but your clients need both capabilities.
  2. AI architecture. Not all AI is the same. Document extraction and generative AI both serve useful but different purposes. Purpose-built tax logic combines these capabilities to create projections that can inform real client decisions.
  3. Client scope. Can the platform handle complex client needs like multi-year projections, state tax modeling, and entity structures? A solution that works well for W-2 households but requires workarounds for business owners will create planning headaches for your team.
  4. Client experience. Tax planning should support the advisor-client conversation, not just your back-office analysis. Evaluate whether the tax platform includes a persistent, secure place for clients to access their financial documents over time and communicate with your team.
  5. Pricing model. Per-upload and per-credit pricing can create friction as you grow, generating unpredictable annual costs and limiting how often advisors choose to use the software. Flat, household-based pricing offers more predictability, especially when it comes as part of an all-inclusive price.
  6. Integration depth. A tax planning solution that’s connected to estate planning analysis helps you move beyond analysis and into real strategy. Evaluate whether your tax scenarios link to estate outcomes and whether the platform reduces the number of disconnected systems in your stack or simply adds another subscription.

If you are looking for a platform that was built to score well across all six of these criteria, Wealth.com’s Tax Planning was designed for exactly that.

See how it works and request a demo here.

Wealth.com Named Exclusive Technology Founding Partner of FMG Suite’s Institutional Intelligence Program

PHOENIX, July 29, 2026: Wealth.com today announced a strategic partnership with FMG Suite, the leading marketing technology platform for wealth management and insurance organizations. Under the partnership, Wealth.com will serve as the Exclusive Technology Founding Partner of FMG’s Institutional Intelligence program.

FMG’s network of more than 80,000 advisors and insurance professionals, as well as the enterprises that support them, will gain access to compliance-friendly estate and tax planning content. Resources will include emails, social media posts, blog articles, downloadable resources and educational marketing assets designed to help advisors engage clients around two of the fastest-growing areas of holistic financial planning.

The partnership will also introduce Wealth.com-powered estate and tax planning website tools, digital experiences and website templates for advisors. FMG’s website team can implement these assets on an advisor’s behalf, creating a turnkey solution that helps firms educate prospects, strengthen client relationships and support business growth.

As part of the partnership, Wealth.com will also develop Estate Snapshot, a website-ready tool powered by Ester®, its proprietary artificial intelligence. Prospects will be able to securely upload estate planning documents, which Estate Snapshot will analyze to generate a concise, one-page summary. This will help advisors prepare more effectively for prospect meetings while creating a new lead generation opportunity.

“Institutional Intelligence is designed to help advisors activate specialized expertise across every marketing channel,” said Susan Theder, chief marketing officer at FMG. “Wealth.com brings exceptional estate and tax planning expertise to the platform, giving advisors ready-to-use resources they can personalize, distribute and use to deepen client relationships.”

Estate and tax planning have become increasingly central to holistic financial advice, yet many advisors still struggle to consistently create timely, compliant educational content around these complex topics.

By combining Wealth.com’s planning expertise with FMG’s leading marketing platform, the partnership gives advisors professionally developed resources they can publish immediately or customize to match their firm’s brand. This makes it easier to educate clients, strengthen relationships and create more meaningful planning conversations.

“The advisors who consistently educate clients are the ones who build deeper relationships and create more opportunities for meaningful planning conversations,” said Tim White, co-founder and chief growth officer at Wealth.com. “FMG has long been the gold standard in advisor marketing, and by combining FMG’s platform with Wealth.com’s estate and tax planning expertise, we’re giving advisors ready-to-use resources that help them educate clients, engage the next generation and differentiate their firms with far less effort.”

The partnership is available immediately at no additional cost to FMG subscribers with access to its Content Library. Wealth.com and FMG will also demonstrate the new capabilities during LPL Focus, taking place Aug. 9–11, 2026.

###

About Wealth.com

Wealth.com is the industry’s leading AI-powered estate and tax planning platform, empowering thousands of wealth management firms to modernize how planning guidance is delivered to clients. Purpose-built for financial institutions, Wealth.com is the only tech-led, end-to-end platform that enables firms to scale estate and tax planning with efficiency, consistency and measurable client impact.

Trusted by some of the largest names in finance, Wealth.com combines proprietary AI, enterprise-grade security and deep legal and tax expertise to support the full spectrum of client needs, from foundational estate plans to advanced estate and tax analysis and reporting. With Wealth.com Tax Planning, firms can deliver more integrated, proactive planning through a single platform.

Wealth.com has been widely recognized for innovation and leadership, earning Top Estate Planning Technology and Top Estate Planning Implementation at the 2025 WealthManagement.com Industry Awards, as well as the #1 estate planning market share in the 2025 Kitces AdvisorTech Study.

About FMG

FMG is the leading marketing and growth platform for financial advisors, insurance professionals and enterprises, empowering them to scale compliant, client-centered marketing that drives organic growth.

Trusted by more than 80,000 financial professionals reaching over 45 million U.S. investors, FMG is consistently ranked number one in market share and customer satisfaction in the T3 Software Survey Report and has been recognized by WealthManagement.com as Best Marketing Automation Platform.

An independent study found that enterprises using FMG achieved Net Promoter Scores nearly four times the industry average, along with improvements in lead conversion, client retention and time saved on marketing tasks. FMG is defining the future of organic growth for financial services firms. For more information, visit fmgsuite.com.

Media Contact

1 2